Timeshare Lien and Judgment Guide
Can a Timeshare Put a Lien on Your House? What Owners Should Know
Unpaid timeshare debt can create lien and collection risk—but the property affected and the stage of enforcement matter.
The key distinction: The more common first risk is a lien or enforcement claim tied to the timeshare interest itself. A claim involving a separate personal home would generally require a different and more advanced legal path, which may include a lawsuit, court judgment, and judgment-enforcement rights under applicable law.
This guidance draws on experience with unpaid timeshare loans, maintenance fees, assessments, collection notices, liens against timeshare interests, foreclosure, lawsuits, court judgments, and broader judgment-enforcement concerns. The property affected and available remedies can vary by debt type, ownership structure, contract, account status, court process, jurisdiction, and applicable property protections. Owners should verify what the notice identifies and whether the matter has progressed beyond enforcement against the timeshare itself.
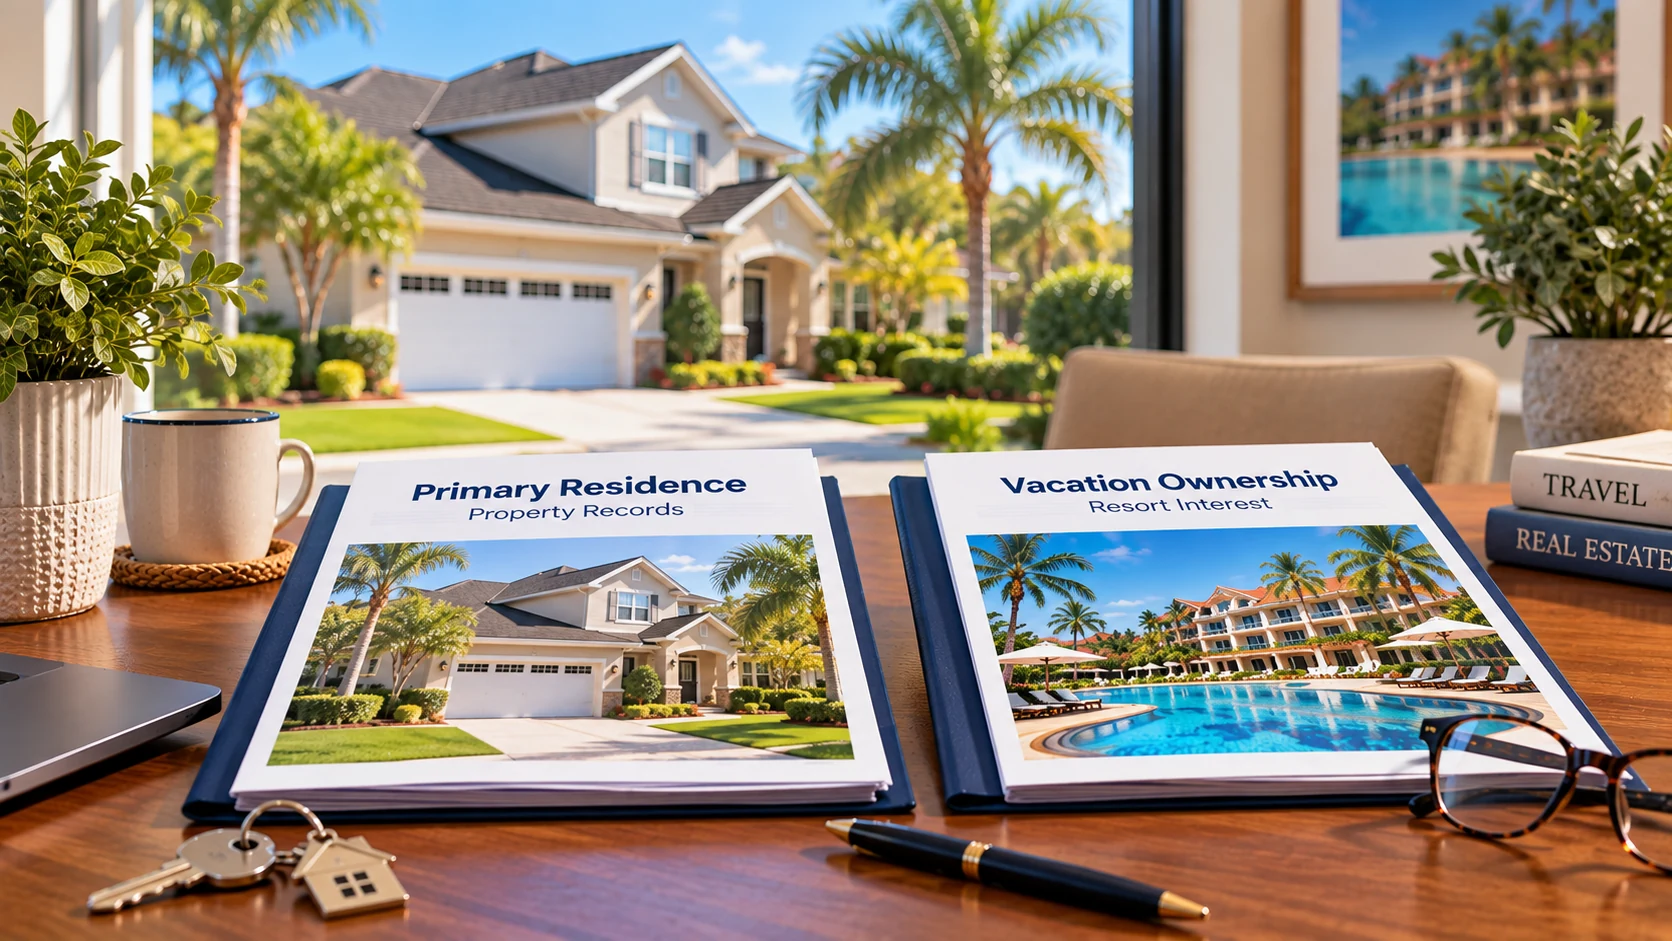
A timeshare interest and a primary residence are separate property interests, which matters when evaluating where a lien or enforcement claim may apply.
Quick Answer
Can a Timeshare Company Put a Lien on Your House?
Usually not automatically. Unpaid timeshare loans, maintenance fees, assessments, taxes, or other ownership-related charges are more commonly enforced against the timeshare interest, deed, account, or usage rights connected to the resort.
A lien involving a separate personal residence would generally require a different legal escalation, which may include a lawsuit, court judgment, and judgment-enforcement remedies available under applicable law. The specific outcome can depend on the debt, contract, court process, state law, and protections that may apply to the property.
Does a timeshare lien automatically attach to your primary residence?
No. A lien tied to a timeshare interest does not automatically become a lien against the owner’s separate personal residence.
Broader enforcement against other property generally involves additional legal steps. What remedies are available depends on the debt, court process, judgment status, jurisdiction, and property protections that may apply.
Start With the Property
Why the Type of Lien Matters
The word lien can make every situation sound equally serious, but the property affected by the lien matters.
A lien tied to the timeshare interest may lead to foreclosure of the timeshare, loss of usage rights, collection activity, added costs, or credit consequences. That is serious, but it is not the same as a lien recorded against your personal home.
A lien involving your personal home usually suggests a more advanced legal path. That is why the next step is to separate the timeshare interest risk from the personal-home risk before deciding how serious the notice may be.
If the notice involves enforcement against the timeshare itself, review Can a Timeshare Be Foreclosed On? for the next stage of that process.
Lien Distinction
Timeshare Lien vs. Lien on Your House
A lien tied to the timeshare interest and a lien against your personal home are different issues. The difference usually depends on what debt exists, what property secures it, and whether the account has escalated into legal action.
Lien on the Timeshare Interest
This is usually tied to unpaid maintenance fees, assessments, taxes, or ownership-related charges connected to the timeshare itself.
- May attach to the timeshare interest, deed, usage rights, or ownership account.
- May allow the resort, association, trustee, or managing entity to pursue timeshare foreclosure.
- Does not automatically mean your primary residence has a lien against it.
- May still create credit, collection, legal, or ownership-related complications.
Lien on Your Personal Home
This is usually a separate legal issue and is not the same as an ordinary timeshare assessment lien.
- May require a lawsuit, judgment, or other legal escalation before broader collection rights apply.
- Depends on the debt type, contract terms, court process, and applicable state law.
- May become a concern if unpaid debt turns into a judgment collection issue.
- Should be reviewed carefully before assuming your home is either protected or immediately at risk.
Enforcement Stages
How Timeshare Debt Can Escalate Beyond the Timeshare
Unpaid timeshare debt does not usually begin with a lien against the owner’s home.
The more common starting point is a delinquent loan, maintenance-fee balance, assessment, tax charge, or other obligation connected to the timeshare account. That may lead to late fees, suspended usage, internal recovery efforts, collections, or a lien against the timeshare interest.
The risk may become broader if the creditor pursues a lawsuit and obtains a court judgment.
A judgment is different from:
- A past-due account statement
- A collection letter
- A lien against the timeshare
- A foreclosure notice involving the timeshare interest
Depending on applicable law, a judgment may create additional collection remedies. Whether those remedies could involve other property—including a personal residence—depends on the debt, court process, available exemptions, and state-law enforcement rules.
Not every unpaid account follows that path. A collection notice does not mean a judgment exists, and a lien against the timeshare does not automatically mean a lien has been recorded against the owner’s home.
If the account is still in the collection stage, review TTCA’s Timeshare Collections guide . If foreclosure has begun, review Can a Timeshare Be Foreclosed On?
No immediate home lien does not mean the debt can be ignored. The first enforcement action may be limited to the timeshare interest, but unpaid balances can still lead to collections, added legal costs, credit reporting, foreclosure, or a lawsuit. The risk may change as the account progresses.
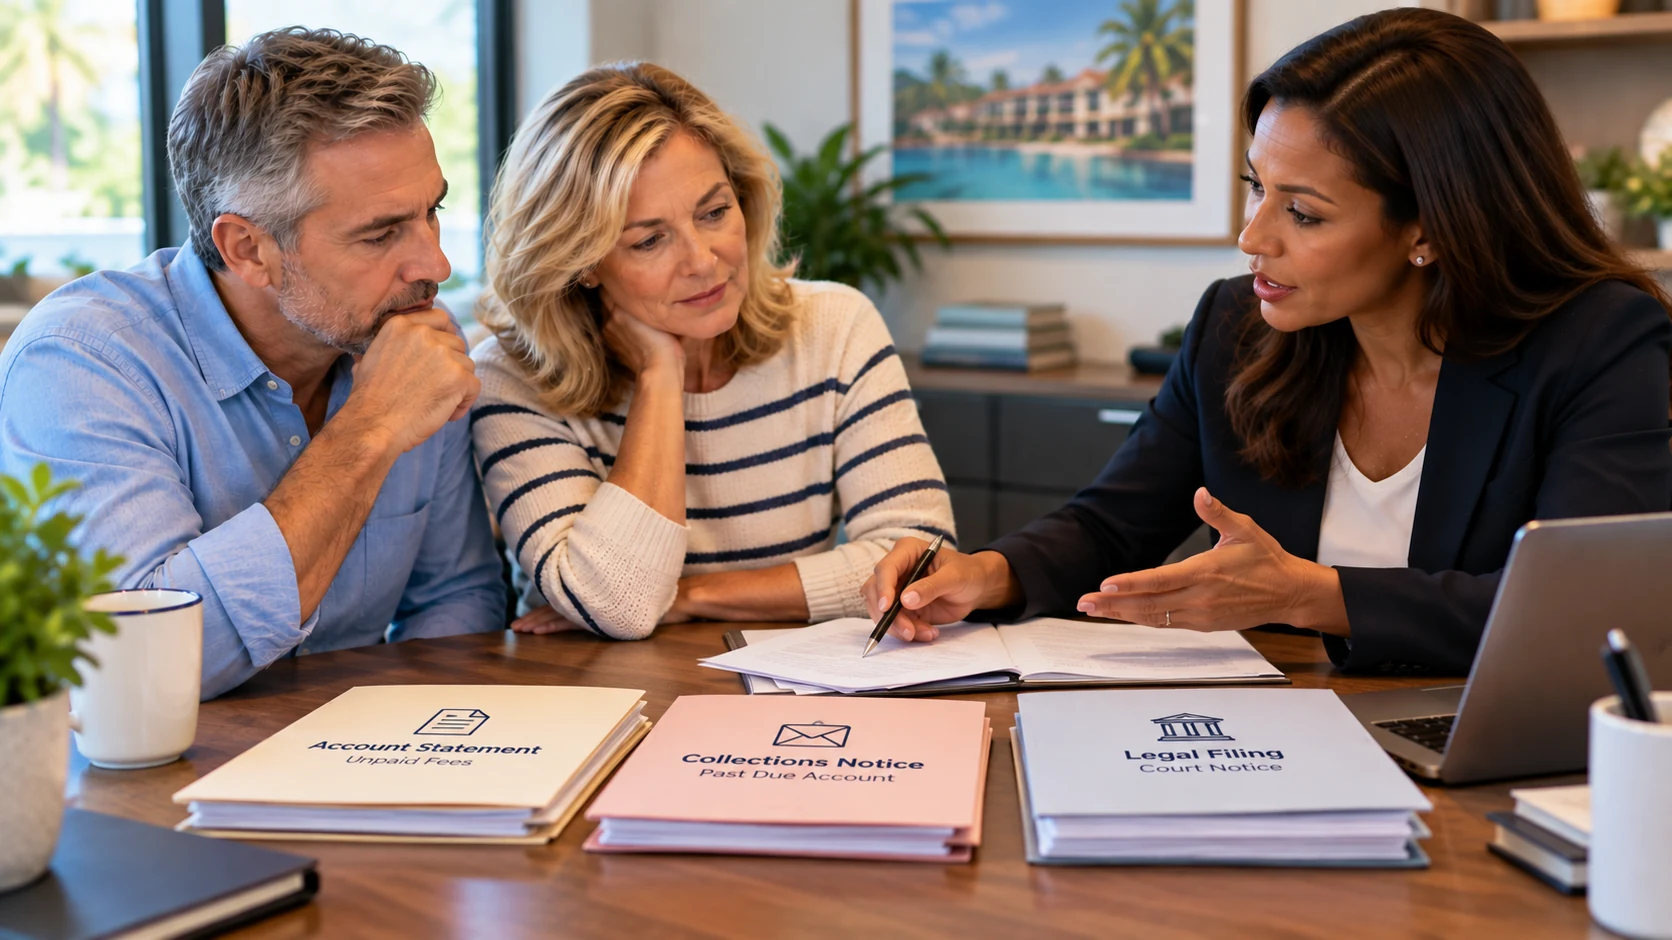
Timeshare debt can move through different stages, from an unpaid account to collections and potentially legal action.
What to Verify
What to Check If You Receive a Timeshare Lien or Collection Notice
Before paying, disputing, ignoring, or reacting to a lien notice, identify the debt, the property or ownership interest named, and whether the matter has entered a court process.
- Confirm whether the notice names the timeshare deed, ownership account, usage rights, or another property.
- Identify what is unpaid: loan payments, maintenance fees, assessments, taxes, or legal costs.
- Verify who sent the notice and whether that party currently controls or collects the account.
- Look for a case number, court name, judgment date, lien-recording information, or response deadline.
- Separate a collection demand from a foreclosure notice, lawsuit, judgment, or recorded property lien.
- Request written clarification if the notice does not clearly identify the affected property and claimed remedy.
TTCA Ownership PathFinder™
Keep, rent, sell or exit?
A lien or collection problem tells you something about the account, but it does not by itself tell you what to do with the ownership.
If you’re deciding whether keeping, renting, selling, or exiting still makes sense, PathFinder can help you compare the four ownership paths after you separate the debt issue from the ownership decision.
Complimentary for TTCA visitors • About 2 minutes
You decide what happens next. We help you understand the paths.
Account Consequences
Can a Timeshare Lien Affect Your Credit or Lead to Foreclosure?
A lien against the timeshare interest can still create serious consequences even when it does not involve the owner’s personal home.
Unpaid loan payments, maintenance fees, assessments, or taxes may lead to collections, credit reporting, loss of usage rights, or foreclosure of the timeshare interest. The exact path depends on the ownership structure, documents, account status, and applicable law.
The lien itself may not be the only source of credit risk. Missed payments, collection accounts, charge-offs, foreclosure reporting, or a court judgment may affect credit separately.
For a deeper explanation of reporting consequences, see Can a Timeshare Affect Your Credit Score?
If the lien is being enforced against the timeshare interest, review Can a Timeshare Be Foreclosed On? What Owners Should Know for the distinction between foreclosure, termination, loss of ownership rights, and any balance that may remain afterward.
A delinquent account and an ownership problem are related, but they are not the same thing. Resolving collections or a lien does not necessarily end the underlying ownership. If your goal has shifted from catching up to finding a legitimate way to transfer the timeshare, Timeshare Specialists offers a transfer-based exit program for owners comparing that path.
See My Exit OptionsThis is one possible ownership-resolution path, not a solution to a lawsuit, judgment, or lien against other property.
A collection notice can signal that unpaid timeshare obligations have moved beyond ordinary billing, but owners should verify what debt, property, and enforcement stage the notice actually involves.
My Take
Don’t Let the Word “Lien” Do All the Thinking for You
If I received a notice involving a timeshare lien, I would not assume from the word lien alone that my home was immediately at risk. But I would not dismiss the notice simply because the timeshare appears to be the property affected.
I would first identify exactly what debt is unpaid, what property or ownership interest the notice names, and whether the account is still in collections or has progressed into foreclosure, a lawsuit, or a court judgment.
Those distinctions tell you much more about the situation than the word “lien” by itself.
Frequently Asked Questions
Timeshare Lien FAQ
Can a timeshare company put a lien on your house?
Usually not automatically. The more common lien risk is tied to the timeshare interest itself. A lien involving the owner’s personal home would generally require a separate legal escalation, such as a lawsuit, court judgment, and available judgment-enforcement rights.
Can unpaid timeshare maintenance fees create a lien?
In some cases, yes. Unpaid maintenance fees, assessments, taxes, or related charges may create a lien against the timeshare interest when the governing documents and applicable law permit it. That is different from automatically placing a lien on the owner’s primary residence.
Does a collection letter mean a lien has been placed on my home?
No. A collection letter generally means someone is attempting to recover an unpaid balance. It does not, by itself, prove that a lawsuit has been filed, a judgment has been entered, or a lien has been recorded against any property.
Can a lien against the timeshare lead to foreclosure?
It may. A lender, association, resort, trustee, or another authorized party may be able to enforce a lien against the timeshare interest through foreclosure or another ownership-termination process. The exact remedy depends on the ownership structure and governing rules.
Can unpaid timeshare debt become a court judgment?
It may if the creditor files a lawsuit and the court enters judgment. A judgment is different from a billing notice, collection letter, or lien against the timeshare interest and may create additional collection remedies under applicable law.
What should I check after receiving a timeshare lien notice?
Confirm what property or ownership interest the notice identifies, what balance is claimed, who sent it, whether a court case exists, whether foreclosure has begun, and what response or cure deadline applies.
The Practical Conclusion
Determine What Property Is Affected Before Deciding What the Notice Means
Unpaid timeshare debt usually creates risk against the timeshare interest first—not automatically against the owner’s personal home. A lien involving a separate residence generally requires a different and more advanced legal path.
Do not treat a collection letter, lien notice, foreclosure notice, lawsuit, and judgment as interchangeable. Before deciding what the notice means or what to do with the ownership, identify the debt, the property or ownership interest affected, and the enforcement stage.
Continue From Here
Follow the Stage Your Timeshare Account Has Actually Reached
Can a Timeshare Be Foreclosed On? What Owners Should Know
Understand when a lien or unresolved default may lead to foreclosure or loss of the timeshare interest.
Can a Timeshare Go to Collections?
See how unpaid timeshare obligations can move from internal billing into collection activity and what to verify at that stage.
Should You Stop Paying Your Timeshare? What Happens Next
Understand what nonpayment can trigger before treating missed payments as a way to resolve the ownership.
Free Timeshare Self-Review
Is the lien concern part of a bigger ownership problem?
The Timeshare Self-Review helps you step back from the immediate account issue and look at how the ownership is working for you overall.
- How often you use it
- Your annual ownership costs
- Your booking experience
- The benefits you actually use
- Fit with your travel habits
- Ownership factors worth reviewing
Private • Self-guided • Instant result. By subscribing, you’ll also receive practical TTCA timeshare guidance and updates.