Timeshare Credit Guide
Can a Timeshare Affect Your Credit Score? What Actually Creates the Risk
Simply owning a timeshare does not automatically damage your credit. The more important question is whether a financial obligation connected to the ownership—such as a purchase loan, delinquent payment, collection account, or other reported activity— appears on your credit file or later becomes reportable.
The decision: Before you stop paying, settle a balance, transfer the ownership, or try to exit, identify which timeshare-related obligation exists, whether it is being reported, and whether the ownership itself has actually been resolved.
This guide separates the timeshare ownership from the financial accounts and payment obligations connected to it. It focuses on purchase financing, maintenance-fee billing, delinquency, collections, foreclosure or other enforcement, and the documentation that shows whether an ownership obligation has actually ended. Potential credit effects vary by account type, reporting party, payment history, ownership status, and escalation stage. This is educational guidance, not legal advice or credit-repair advice.
On This Page
- Can a timeshare affect your credit?
- What creates credit exposure?
- What changes the answer?
- Does a timeshare show on your credit report?
- Loans, fees, collections and foreclosure
- What happens if you stop paying?
- My Take
- Can you exit without hurting your credit?
- Exit-company credit promises
- What to verify before acting
- Frequently asked questions
- TTCA Decision
A timeshare may affect credit through financing, missed payments, collections, or other reported account activity—not simply because the ownership exists.
Quick Answer
Can a Timeshare Affect Your Credit Score?
Yes, but usually because of a financial obligation connected to the timeshare—not simply because you own one.
A financed timeshare may appear on your credit report when the lender reports the balance and payment history. Late or missed payments on that loan can therefore create direct credit exposure.
A paid-off timeshare may not appear as an active credit account. Maintenance fees and assessments may also begin as internal resort or association billing, although unresolved balances can become more consequential if they progress into collections or another enforcement process.
What parts of a timeshare can affect your credit?
A timeshare can affect credit through financial obligations connected to the ownership, including reported purchase financing, delinquent payments, collection activity, or other reported account status.
Simply owning a timeshare is not the same thing as having a reported credit account. The type of obligation, who controls it, whether it is current, and whether negative activity has been reported determine the more relevant credit exposure.
Credit Exposure
What Actually Creates Credit Exposure?
The word timeshare can describe several different financial obligations, and they do not all interact with credit in the same way.
A financed timeshare purchase
When an owner finances the purchase, the lender may report the loan balance and payment history. That creates the clearest direct connection between the timeshare and the owner’s credit file.
If financing remains, do not assume that changing the ownership automatically eliminates the debt. TTCA’s guide to getting out of a timeshare when you still owe money explains why the financing and ownership need to be evaluated separately.
Late or missed loan payments
A missed loan payment changes the status of the financial account. It does not by itself end the timeshare. An owner can therefore have a delinquent financing obligation and an ownership or membership that has not yet been formally resolved.
Unpaid maintenance fees or assessments
Maintenance fees, assessments, club dues, and similar recurring charges may be billed by a resort, association, developer, management company, or another ownership entity. These charges may not appear as monthly credit accounts, but an unpaid balance can become more consequential as the account moves beyond ordinary billing.
If you are considering intentionally withholding payments, review Should You Stop Paying Your Timeshare? before treating nonpayment as an ownership strategy.
Collections or enforcement
Once an unresolved timeshare debt reaches collections or another formal recovery process, the situation has moved beyond ordinary billing. At that stage, identify which debt is being pursued, who controls it, what a payment or settlement would actually resolve, and whether the underlying ownership remains active.
If a collector is already involved, use TTCA’s Timeshare Collections guide for the narrower collections-stage decision.
What Changes the Answer
The Account Behind the Timeshare Matters More Than the Label
- Active financing Is there still a purchase loan or another financed balance?
- Payment status Is the loan, maintenance-fee account, assessment, or other balance current, late, or delinquent?
- Reporting party Which lender, servicer, collector, resort, association, or other party controls the account?
- Current reporting Does any related account or negative status already appear on your credit reports?
- Escalation stage Is the obligation still being billed internally, already in collections, or subject to enforcement?
- Ownership status Has the timeshare actually been transferred, surrendered, foreclosed, terminated, or otherwise removed from your name?
- Written proof What documentation confirms what debt was resolved and what ownership obligations remain?
Credit Report
Does a Timeshare Always Show Up on Your Credit Report?
No. Simply owning a timeshare does not mean the ownership will appear as an active account on your credit report.
A financed timeshare is more likely to appear when the lender reports the loan balance and payment history. A paid-off ownership may not appear as an active credit obligation, particularly when the remaining annual charges are billed internally by the resort, association, developer, or management company.
That distinction can create false confidence. An owner may review a credit report, find no timeshare account, and conclude that the ownership cannot affect credit. But an account that does not appear today is not necessarily an obligation that could never create later credit consequences.
The situation may change if a reported loan becomes delinquent, an unpaid ownership balance moves into collections, another party begins furnishing account information, or foreclosure or another enforcement process begins.
Can a paid-off timeshare still create credit concerns?
A paid-off timeshare may have less direct loan-related credit exposure, but paid-off financing does not necessarily eliminate maintenance fees, assessments, collection risk, or ownership obligations.
A timeshare that is absent from your credit report today should not automatically be treated as financially or contractually resolved.
Important Distinction
Loans, Maintenance Fees, Collections, and Foreclosure Are Not the Same Thing
These obligations can overlap, but they are different stages or account types. Treating them as interchangeable can make it harder to understand what a payment, settlement, transfer, or exit would actually resolve.
| Situation | What it means | When credit concerns become more relevant | What to verify |
|---|---|---|---|
| Timeshare purchase loan | Financing used to purchase the ownership | When the lender reports the account and payment history | Lender, balance, payment status, payoff or release |
| Maintenance fees or assessments | Recurring or additional ownership charges | When balances become delinquent and progress beyond ordinary internal billing | Amount due, billing party, account status |
| Collections | An unpaid obligation has moved into a recovery process | When negative activity is reported or the debt progresses further | Creditor, collector, balance, proposed resolution |
| Foreclosure or enforcement | A formal remedy involving the ownership or associated obligation | Consequences depend on the ownership, financing, documents, and process involved | Ownership type, notices, account status, remaining debt |
A collection account and a foreclosure are not interchangeable. Collections concern recovery of an unpaid balance; foreclosure concerns an enforcement process against an ownership interest or related security. Depending on the ownership structure, one may occur without the other or they may appear at different stages.
If the matter has already reached foreclosure or another ownership-enforcement stage, see Can a Timeshare Be Foreclosed On?
Get clearer timeshare guidance.
Understand the account, ownership, and decision before taking the next step.
Before Nonpayment
What Happens If You Stop Paying a Timeshare?
Stopping payments changes the status of an account; it does not prove that the timeshare has ended.
If an owner stops making payments on a financed purchase, the loan may become delinquent while the ownership question remains unresolved. If the owner stops paying maintenance fees or assessments, a separate delinquency may develop while annual charges or other ownership obligations continue.
If both obligations exist, the owner may be dealing with more than one account and more than one potential consequence.
For the full nonpayment analysis, review Should You Stop Paying Your Timeshare? What Happens Next .
My Take
The Credit Report Is Only Half of the Answer
If this were my ownership, I would not make a payment or nonpayment decision based only on whether I could see the timeshare on my credit report today.
I would first identify the obligation, who controls it, whether it is current, and what would happen to the ownership if that obligation were paid, settled, or left unpaid.
A clean credit report does not necessarily prove that the ownership is finished. And resolving a delinquent account does not necessarily prove that future maintenance fees or other ownership responsibilities have ended.
Until those two questions are separated, you may not know whether you are solving a credit problem, an ownership problem, or both.
TTCA Ownership PathFinder™
Keep, rent, sell or exit?
A credit concern does not automatically mean exiting is the right answer—the first question is what ownership problem you are actually trying to solve.
PathFinder can help you compare whether keeping, renting, selling, or exiting deserves closer consideration based on how you use the ownership, what it costs, and what you want next.
Complimentary for TTCA visitors • About 2 minutes
You decide what happens next. We help you understand the paths.
Ownership resolution should be documented through the parties that actually control the account, transfer, surrender, or other ownership process.
Credit-Sensitive Exit
Can You Exit a Timeshare Without Hurting Your Credit?
Exiting a timeshare does not automatically damage your credit. The greater concern is what happens to the loan, maintenance fees, assessments, and account status while the ownership is being resolved.
A lower-risk path generally involves keeping required obligations current until a recognized resolution has been completed, or obtaining clear written instructions from the parties that control those obligations.
Examples of documented ownership resolutions may include:
- completion of a valid rescission;
- an approved surrender or deed-back;
- a completed resale or transfer;
- foreclosure or another formal ownership process; or
- another written resolution recognized by the relevant parties.
The important word is completed.
Submitting a surrender request does not mean it was approved. Hiring an exit company does not mean the loan has been released. Finding someone willing to take the timeshare does not mean the developer, association, lender, or other required party has recognized the transfer.
Credit exposure can develop while an attempted exit is still incomplete if required payments become delinquent.
If a legitimate resale or transfer is a realistic path for your ownership and you want outside help evaluating it, you can explore resale or transfer help through Timeshare Specialists . That is one possible outside-help route, not a substitute for confirming what your lender, resort, association, or developer requires.
What Owners Often Miss
Why an Exit Company Cannot Guarantee Credit Protection
An exit company does not control every party involved in a timeshare account. It generally does not control how a lender reports an account, whether a resort or association continues billing, when an unpaid balance progresses to collections, or whether a developer accepts a surrender.
That means a promise such as “we will protect your credit” deserves closer examination. The useful question is not simply whether the company says the ownership will be resolved. It is: What happens to each financial obligation while the company is pursuing that result?
Before relying on a credit-related assurance from any outside provider, determine:
- whether loan and fee payments are supposed to continue;
- who is communicating with the lender, developer, or association;
- what happens if the attempted exit takes months; and
- what written documentation will prove that both the ownership and the relevant debt have been addressed.
Before You Act
Before You Pay, Stop Paying, Settle, or Exit
A timeshare credit decision becomes much clearer when you build two separate records: one for the financial accounts and one for the ownership.
- Check your credit reports. Identify any timeshare-related loan, collection account, or other reported activity.
- List every timeshare obligation. Separate purchase financing from maintenance fees, assessments, club dues, collection balances, and other charges.
- Confirm each account’s status. Determine what is current, late, delinquent, in collections, or already subject to enforcement.
- Identify who controls each obligation. That may be a lender, developer, association, management company, collector, or another party.
- Verify the ownership status separately. Determine whether the deed, points ownership, membership, or other interest remains in your name.
- Ask what would prove resolution. A payment receipt, settlement letter, deed transfer, surrender acceptance, lender release, or another document may answer different parts of the problem.
- Do not assume one document resolves everything. The debt and the ownership may require separate confirmation.
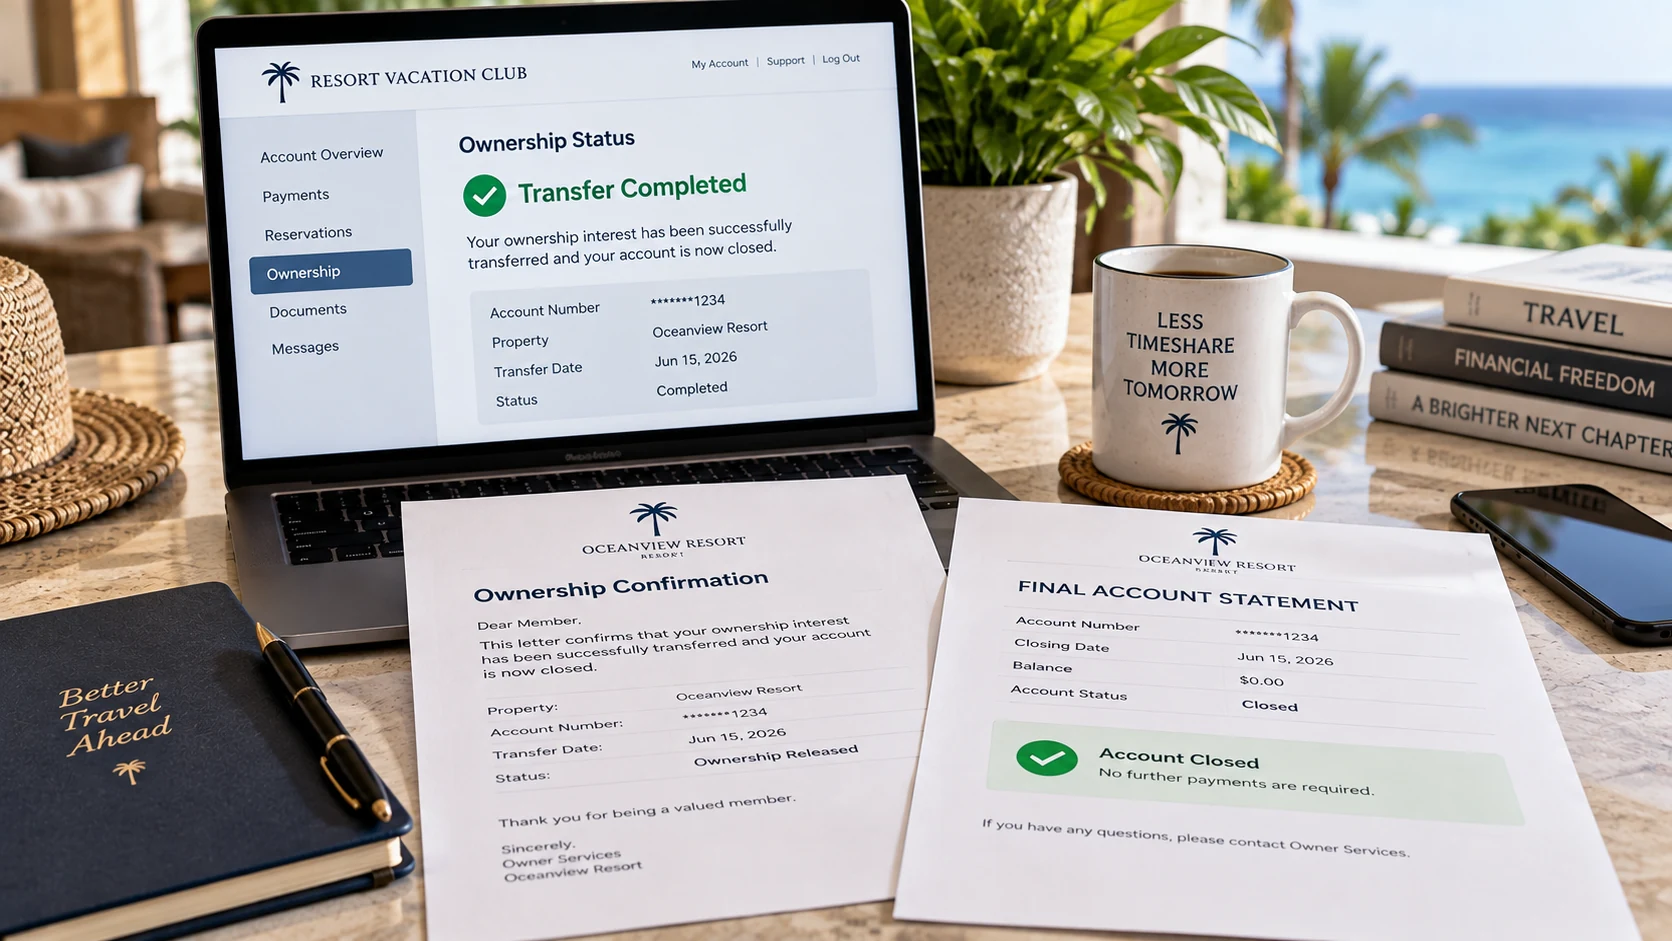
Resolving the financial account and resolving the ownership are separate steps. Written confirmation of both provides a much clearer picture of what has actually ended.
Frequently Asked Questions
Timeshare Credit FAQ
Can a timeshare affect your credit score?
Yes. A timeshare can affect your credit when a financial obligation connected to it—such as a reported purchase loan, late payment, collection account, or other negative account activity— is reported. Simply owning a paid-off timeshare does not automatically lower a credit score.
Does a timeshare always show up on your credit report?
No. A financed timeshare may appear when the lender reports the account and payment history. A paid-off ownership may not appear as an active credit account. However, an obligation that is not reported today could create later credit exposure if an unpaid balance escalates.
Does timeshare financing affect your credit?
It can. When a lender reports a timeshare loan, the balance and payment history may appear on the owner’s credit file. Late or missed payments on that reported loan can therefore create direct credit exposure.
Can unpaid timeshare maintenance fees hurt your credit?
Unpaid maintenance fees may begin as an internal ownership balance rather than a reported credit account. Credit exposure may become more significant if the debt progresses into collections or another enforcement or reporting process.
Can a timeshare collection account affect your credit?
It may. Once a timeshare debt reaches collections, the reporting party, account status, and collection process become important. Owners should verify the debt and the ownership separately because settling a collection account does not necessarily end the timeshare.
Does paying a delinquent timeshare balance remove negative credit history?
Not necessarily. Paying or settling a balance may update the account status without necessarily removing earlier reported activity. It also does not by itself prove that the underlying timeshare ownership has ended.
Can you get out of a timeshare without hurting your credit?
It may be possible to resolve a timeshare without creating avoidable delinquency when required obligations remain current while a recognized surrender, transfer, resale, rescission, or other resolution is completed. The key is confirming what happens to both the debt and the ownership rather than assuming that starting an exit process resolves either one.
TTCA Decision
The Timeshare Itself Is Not the Whole Credit Question
A timeshare does not affect credit simply because you own it. Credit exposure usually comes from a financial obligation connected to the ownership—such as reported financing, delinquent payments, collections, or another enforcement process.
Before deciding to pay, stop paying, settle, transfer, or exit, verify two things separately: what is happening to the financial account and what is happening to the ownership. A resolution is much clearer when both answers are documented.
Continue From Here
Follow the stage your credit concern has actually reached.
Should You Stop Paying Your Timeshare?
Understand the difference between loan default and maintenance-fee nonpayment before intentionally missing payments.
Can a Timeshare Send You to Collections?
See how timeshare debt may move into collections and what to verify before paying or settling.
Can a Timeshare Be Foreclosed On?
Understand when foreclosure may enter the picture and how it differs from collections or ordinary delinquency.
Free Timeshare Self-Review
Is the credit concern part of a bigger ownership problem?
Use TTCA’s free Timeshare Self-Review to look beyond the credit issue and consider how the ownership is working for you overall.
- Your current ownership costs
- How often you actually use it
- Your booking experience
- The benefits you really use
- Fit with your current travel habits
- What may deserve a closer look
Private • Self-guided • Instant result. By subscribing, you’ll also receive practical TTCA timeshare guidance and updates.