Timeshare Foreclosure Guide
Can a Timeshare Be Foreclosed On? What Owners Should Know
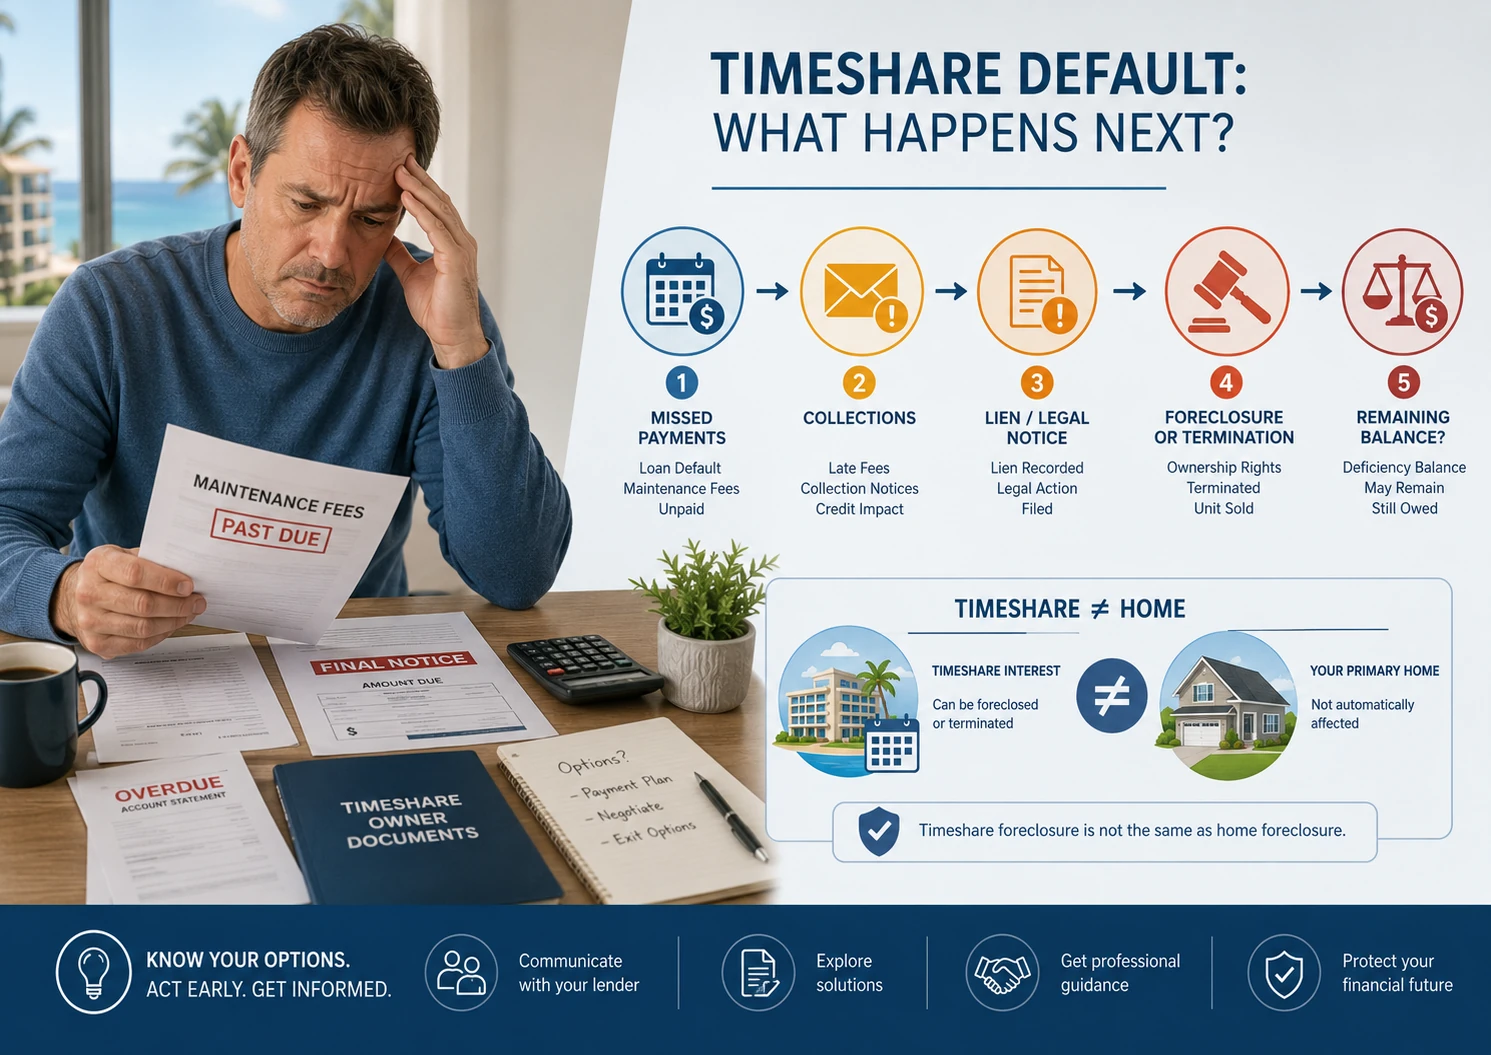
Yes, in some cases—but the path to foreclosure depends on what is unpaid and what type of timeshare interest you actually own.
A default involving a purchase loan may follow a different path from unpaid maintenance fees or assessments, and a deeded interest may be treated differently from a contractual membership. Before assuming foreclosure will occur—or that it will solve the ownership problem—identify the obligation, ownership structure, enforcement stage, and any balance that could remain afterward.
About This Guidance: TTCA evaluates timeshare foreclosure by separating the ownership interest from the debt or account default that may trigger enforcement. This guidance focuses on loan and maintenance-fee defaults, deeded and contractual ownership structures, collections and lien activity, the progression toward foreclosure, potential remaining balances, and the written confirmation owners should obtain before assuming foreclosure will fully resolve the account.
How It Works
How a Timeshare Account Can Progress Toward Foreclosure
There is no single foreclosure sequence that applies to every timeshare. The practical starting point is to identify the default, determine what type of ownership is involved, confirm how far enforcement has progressed, and then verify what a completed foreclosure would actually resolve.
TTCA Framework Insight: Losing the timeshare interest and resolving the financial account are related but separate outcomes. Foreclosure should not be treated as a complete exit until both have been verified.
Before You Assume Foreclosure Will End Everything
The Ownership, the Default, and the Remaining Balance Must Be Reviewed Separately
A foreclosure outcome may depend on whether the default involves a purchase loan, maintenance fees, special assessments, a deeded interest, a membership product, collection activity, or a claimed balance after the ownership ends. The Timeshare Decision Intelligence Report™ helps organize the documents, account status, obligations, and unresolved questions before you rely on foreclosure as an ownership solution.
Need a clearer view of what foreclosure may—and may not—resolve?
Review the Report Option Or continue with the foreclosure distinctions belowWhich Timeshare Defaults Can Lead to Foreclosure?
Foreclosure risk usually begins with an unresolved obligation, but the type of obligation determines who may pursue the account and what interest may be enforced.
A purchase-loan default generally involves money borrowed to acquire the timeshare. A maintenance-fee default involves the ongoing cost of keeping the ownership active. The same owner can experience either type of default—or both at the same time.
Not every missed payment immediately leads to foreclosure. An account may first pass through internal recovery, collection activity, notices, or other enforcement steps. This page focuses on the later stage in which a lender, association, developer, or another party may seek to enforce rights against the timeshare interest.
Default Comparison
Loan Default and Maintenance-Fee Default Can Create Different Risks
Both defaults may place the timeshare interest at risk, but they arise from different obligations and may involve different creditors, documents, and enforcement rights.
Timeshare Loan Default
This occurs when required payments on the debt used to purchase the timeshare remain unpaid.
- Usually involves the lender or loan servicer.
- May lead to collection activity before foreclosure.
- Can create credit consequences before the ownership is foreclosed.
- May leave questions about any balance remaining after enforcement.
Maintenance-Fee or Assessment Default
This can occur even when the original purchase loan has been fully paid.
- May involve the resort, association, developer, or management company.
- Can include maintenance fees, assessments, taxes, or related charges.
- May create lien or foreclosure rights against a deeded interest.
- Can continue until the ownership is formally resolved.
Why the Type of Timeshare Ownership Matters
Foreclosure usually requires an interest or lien right that can be enforced. That is why the ownership structure matters before assuming every timeshare default follows the same process.
A deeded timeshare may involve a recorded real estate interest. If the loan, maintenance fees, assessments, taxes, or association charges tied to that interest remain unpaid, the creditor or association may have foreclosure rights under the governing documents and applicable law.
A right-to-use product or vacation-club membership may be different. Rather than foreclosing on real estate, the company may suspend reservations, cancel membership rights, terminate the contract, pursue collections, or seek payment through another enforcement process.
Points ownership can fall into either category. Points may be connected to a deed, a trust interest, a membership, or another contractual structure. The points themselves do not reveal what is legally owned or what remedies may be available after default.
Ownership Structure
Foreclosure, Termination, and Loss of Use Are Not Always the Same
The enforcement path may depend on whether the owner holds a deeded real estate interest, contractual usage rights, or points connected to another ownership structure.
Deeded Timeshare
A recorded ownership interest may be subject to liens and foreclosure when the loan or required ownership charges remain unpaid and the documents and applicable law permit enforcement.
Right-to-Use or Club Membership
The company may suspend reservations, cancel usage rights, terminate membership, or pursue unpaid balances without using a traditional real estate foreclosure process.
Points-Based Ownership
Points may be connected to a deed, trust, membership, or contractual interest. The documents—not the points balance—determine what is owned and what may happen after default.
Is Timeshare Foreclosure the Same as Home Foreclosure?
Not exactly.
A home foreclosure usually involves a mortgage secured by a residence or other real property. The lender pursues the property that secured the mortgage after the borrower defaults.
A timeshare foreclosure is generally narrower. The creditor, association, or other authorized party usually pursues the timeshare interest connected to the unpaid obligation.
That does not automatically place the owner’s personal residence into foreclosure. However, owners should not interpret that distinction to mean the timeshare default is harmless.
The account may still involve:
- Collection activity
- Negative credit reporting
- Legal or foreclosure costs
- Loss of usage and ownership rights
- A lawsuit or judgment
- A claimed balance after the timeshare interest is removed
Whether unpaid timeshare debt could eventually affect property beyond the timeshare is a separate question. That risk may depend on whether the creditor files a lawsuit, obtains a judgment, and gains broader collection rights under applicable law. See Can a Timeshare Put a Lien on Your House? for a closer explanation of the difference between a lien against the timeshare interest and a lien involving an owner’s personal residence.
Important Difference
Home Foreclosure and Timeshare Foreclosure Target Different Interests
Both may arise from default, but the property securing the obligation and the practical consequences are usually different.
Home Foreclosure
The lender generally enforces a mortgage or lien against the residence or other real estate that secured the loan, potentially resulting in the loss of that property.
Timeshare Foreclosure
The enforcement usually targets the timeshare interest itself. The owner may lose the timeshare while still facing credit, collection, legal-cost, or remaining-balance questions.
Risk Point
Credit and Collection Consequences May Begin Before Foreclosure
Owners should not assume that the account remains financially neutral until a foreclosure is completed. Missed loan payments, unpaid fees, collection accounts, charge-offs, or related activity may be reported or pursued before any foreclosure action reaches its final stage.
Foreclosure is only one possible consequence of unresolved default. For a deeper explanation of reporting and credit effects, see Can a Timeshare Affect Your Credit Score?
Foreclosure vs. Collections vs. a Lawsuit
Foreclosure, collections, and a lawsuit are different enforcement paths, even though the same account may move through more than one of them.
Collections generally focuses on recovering an unpaid balance. The creditor or collection agency may send notices, make payment demands, report the account, or propose a settlement.
Foreclosure generally focuses on enforcing a lien or ownership interest connected to the timeshare. The result may be the loss of a deeded interest or another formal end to the ownership rights.
A lawsuit may seek a court judgment for unpaid amounts, legal costs, or another claimed contractual obligation. A judgment may create collection rights that are separate from the foreclosure of the timeshare itself.
An account may begin with internal recovery efforts, move to third-party collections, and later become a foreclosure or lawsuit matter. But not every account follows that progression, and collection activity does not prove that foreclosure has already begun.
For the earlier collection stages, use the published guides Can a Timeshare Go to Collections? and What to Do After Receiving a Timeshare Collection Notice. This article focuses on the later question of whether the ownership interest may be taken and what obligations may remain afterward.
What Happens After a Timeshare Foreclosure?
A completed foreclosure may end the owner’s interest in the timeshare, but it should not automatically be treated as proof that every obligation has been resolved.
The owner may lose the deeded interest, reservation rights, club access, and other benefits connected to that ownership. However, the financial outcome may depend on the foreclosure terms, the type of debt, the amount recovered through the process, and whether the creditor claims additional costs or a remaining balance.
After foreclosure, owners should look for written documents confirming:
- The date the ownership interest ended
- Who took or accepted the timeshare interest
- Whether usage and membership rights were terminated
- Whether future maintenance-fee obligations stopped
- Whether the loan or fee account was closed
- Whether legal, collection, or foreclosure costs were added
- Whether any remaining balance is still claimed
- How the outcome may be reported to credit bureaus
A foreclosure notice, public record, or loss of reservation access may show that enforcement occurred, but it may not answer every financial question.
The critical issue is not only whether the timeshare was taken. It is whether the owner has written proof showing what ended and what, if anything, remains.
Owner takeaway: Foreclosure may end the timeshare interest, but it should not be treated as a clean exit without written proof showing when the ownership ended, whether future fees stopped, whether the account closed, and whether any loan, legal, collection, or remaining balance is still being claimed.
Can You Avoid Timeshare Foreclosure?
In some cases, foreclosure may still be avoidable, but the available options usually depend on how far the account has progressed.
An owner who has recently missed a payment may have more flexibility than someone whose account has already moved through collections, lien enforcement, legal review, or a scheduled foreclosure process.
Possible options may include bringing the account current, requesting a payment arrangement, seeking a hardship review, or asking whether the developer or association offers a surrender or deed-back program.
Those options are not guaranteed.
Many voluntary surrender programs require the purchase loan to be paid off, maintenance fees to be current, and the account to remain in good standing. Once the account becomes seriously delinquent, the developer may be less willing to accept a voluntary return.
The owner should first identify:
- What obligation is unpaid
- Who currently controls the account
- Whether a lien has been recorded
- Whether foreclosure has formally begun
- Whether a response or cure deadline applies
- Whether any voluntary resolution remains available
A loan servicer, association, collection agency, or law office may each have a different role. The owner should not assume that contacting one party automatically resolves obligations controlled by another.
The earlier the account status is verified, the more opportunity there may be to compare a negotiated or voluntary outcome with foreclosure.
Action Step
Verify the Foreclosure Stage Before Choosing a Response
Identify the ownership, the unpaid obligation, the party enforcing it, and the current stage before assuming foreclosure is unavoidable or will fully resolve the account.
- Confirm whether the ownership is deeded, right-to-use, points-based, trust-based, or a club membership.
- Separate the purchase loan from maintenance fees, assessments, taxes, and association charges.
- Identify whether the account remains internal, is in collections, has a recorded lien, or is already in foreclosure.
- Review every notice for cure dates, response deadlines, legal contacts, and the amount claimed.
- Ask whether payment, hardship, surrender, deed-back, settlement, or another documented resolution remains available.
- Request written confirmation of what happens to the ownership, future fees, loan account, and any remaining balance.
Before assuming foreclosure is unlikely, harmless, or unavoidable, the next step is to review what is actually unpaid and which enforcement path may apply. A loan default, unpaid maintenance fee balance, lien notice, collection account, and lawsuit threat can create different kinds of risk.
❓ Frequently Asked Questions
These questions address when a timeshare may be foreclosed on, what interest may be affected, and what owners should verify before assuming the account has been resolved.
Can a timeshare be foreclosed on for unpaid maintenance fees?
In some cases, yes. Unpaid maintenance fees, assessments, taxes, or association charges may create a lien or enforcement right against a deeded timeshare interest. Whether foreclosure is available depends on the ownership documents and applicable law.
Can a paid-off timeshare still be foreclosed on?
Yes. Paying off the original purchase loan does not eliminate maintenance fees, assessments, taxes, or other ongoing ownership charges. Those obligations may continue until the ownership is legally resolved.
Is timeshare foreclosure the same as home foreclosure?
No. Timeshare foreclosure generally targets the timeshare interest, not automatically the owner’s personal home. However, collections, a lawsuit, a judgment, or other remedies may create separate financial questions that should be reviewed.
Does foreclosure mean I no longer own the timeshare?
A completed foreclosure may end the ownership interest and related usage rights, but owners should obtain written confirmation showing the effective date and whether future maintenance-fee obligations have stopped.
Does timeshare foreclosure eliminate the remaining balance?
Not necessarily. The creditor may still claim loan amounts, unpaid fees, legal costs, collection charges, or another balance depending on the documents, foreclosure outcome, and applicable law. Written confirmation is essential.
Can timeshare foreclosure affect my credit?
It can. Credit effects may begin before foreclosure through missed-payment reporting, collections, or charge-off activity. Foreclosure or related debt activity may create additional reporting consequences.
Can timeshare foreclosure be avoided?
Possibly. Payment arrangements, hardship review, surrender, deed-back, settlement, or another resolution may be available, particularly before the account reaches an advanced enforcement stage. Eligibility varies.
Bottom Line
A timeshare can sometimes be foreclosed on when an unpaid loan, maintenance-fee balance, assessment, tax, or association charge creates an enforceable default or lien against the ownership interest.
The outcome depends on the ownership structure. A deeded timeshare may face foreclosure, while a right-to-use product, club membership, or certain points-based interests may instead be suspended, canceled, or terminated.
Timeshare foreclosure generally targets the timeshare—not automatically the owner’s personal home—but it may still involve collections, credit reporting, legal costs, or a claimed remaining balance.
Foreclosure is only one possible outcome and should not be treated as the preferred way to end an ownership. For a broader comparison of surrender, resale, transfer, developer programs, and other potential paths, see the Timeshare Exit Guide: How to Get Out of a Timeshare.
Understand What May End—and What Financial Obligations Could Remain
A foreclosure decision may depend on the ownership structure, purchase loan, maintenance-fee balance, collection status, lien rights, notices, account history, and the documents governing what happens after enforcement. The Timeshare Decision Intelligence Report™ helps organize those details, identify material risks and verification gaps, and clarify which resolution paths may still be realistic before you assume foreclosure will close everything.
Get the Timeshare Decision Intelligence Report™ Customized ownership review • Decision-support report • No exit-company sales pitchIndependent educational decision support. This is not legal or financial advice, foreclosure representation, debt negotiation, contract cancellation, a resale service, or an exit service.
Related Guides
These published guides explain the collection, credit, lien, and nonpayment issues that may arise before or alongside timeshare foreclosure.
Collections and Credit Consequences
- What Happens When Timeshare Maintenance Fees Go to Collections?
Understand how unpaid fees may move into collections and what collection activity may mean for the account. - Can a Timeshare Affect Your Credit Score?
Review how missed payments, collections, charge-offs, foreclosure, and related reporting may affect credit.
Before Stopping Payments
- Should You Stop Paying Your Timeshare? What Happens Next
Compare the possible consequences of nonpayment before deciding whether to stop making required payments. - What Happens If You Stop Paying Timeshare Maintenance Fees?
Follow how unpaid maintenance fees may progress through late charges, suspended use, collections, liens, or foreclosure risk.