Post-Rescission Options Guide
Can You Cancel a Timeshare After the Rescission Period?
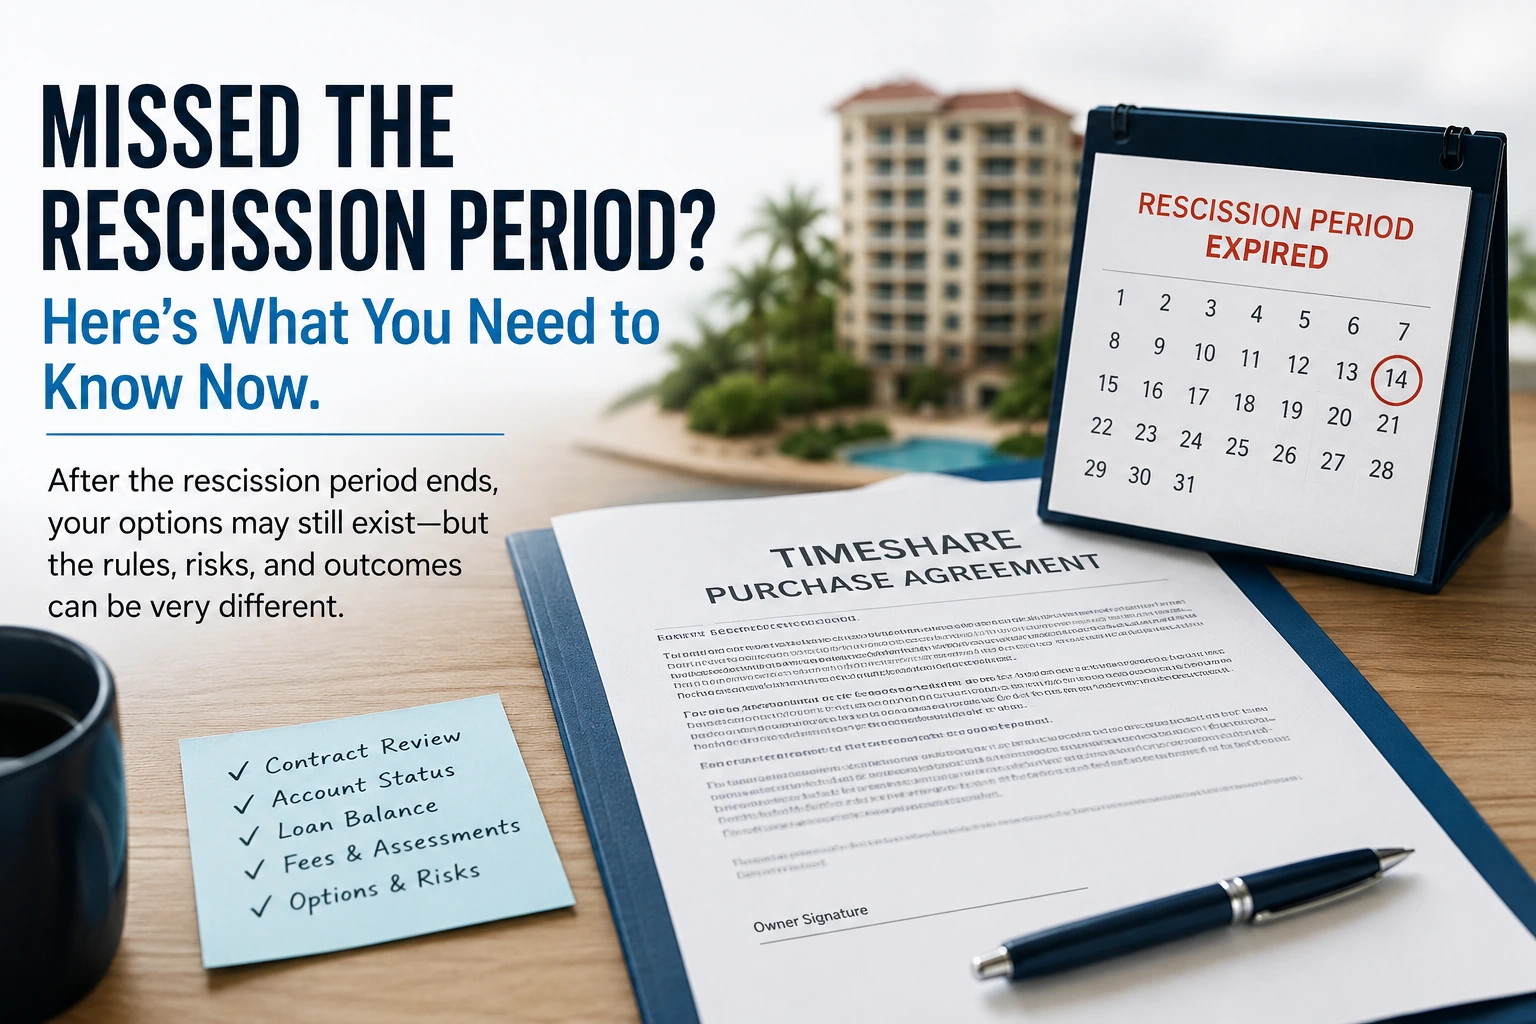
Missing the rescission deadline usually changes the process. It does not necessarily mean that every possible path has disappeared.
Once the ordinary cancellation window closes, the developer generally is not required to reverse the purchase simply because the owner has changed their mind. Surrender, deed-back, resale, transfer, negotiation, or contract review may still deserve consideration—but each has its own requirements and limitations. This guide helps you identify what remains active, which paths may fit the ownership, and what written proof would show that the responsibility has actually ended.
Reassess the Ownership
Four questions determine what may come next
After rescission, the focus shifts from sending a cancellation notice to identifying a documented resolution path.
- Has the rescission deadline and delivery history been verified?
- What ownership, loan, fees, and account balances remain active?
- Which surrender, transfer, resale, or review options may apply?
- What final documentation would end future responsibility?
Stop looking for a generic late-cancellation letter. Determine which documented path could resolve the ownership you actually have.
About this guidance: Timeshare Travel Club Authority’s guidance draws on experience with rescission deadlines, contract cancellation instructions, developer surrender and deed-back programs, resale and transfer restrictions, hardship reviews, financing, unpaid balances, account standing, and documentation used to confirm that an ownership has ended. Post-rescission options can vary by contract, ownership structure, loan status, developer policy, account condition, transfer requirements, and the specific facts involved, so owners should verify both the available pathway and what happens to the ownership, financing, past-due amounts, and future fees.
How It Works
How to Cancel a Timeshare After the Rescission Period: What to Do Next
Once the contractual or statutory rescission window has closed, ordinary rescission is generally no longer the process being used. The next step is to verify the deadline, understand the ownership and account status, and determine which post-rescission resolution paths may realistically apply.
TTCA Framework Insight: After the rescission period, “canceling” a timeshare usually means finding another documented path that ends the ownership or contractual obligation. It should not be confused with exercising a rescission right after the deadline has already expired.
After the Cancellation Window Closes
Understand Which Paths May Still Apply to Your Ownership
Once the rescission period ends, the realistic options may depend on the contract, ownership structure, loan balance, account standing, developer policies, transfer restrictions, and unresolved fees. The Timeshare Decision Intelligence Report™ helps organize those details and identify verification gaps before you stop paying, hire an exit company, or rely on a surrender or transfer promise.
Need a clearer view of the ownership before choosing your next step?
Review the Report Option Independent decision support • No exit-company sales pitchWhat Options May Still End a Timeshare After the Rescission Period?
Once the rescission period has ended, there usually is not one universal “late cancellation” process. Instead, an owner may need to qualify for another path that can formally end or transfer the ownership.
The realistic options depend on the ownership structure, loan balance, account standing, developer policies, transfer requirements, and the specific facts involved. Each path also requires different proof that the ownership and future responsibility have actually ended.
Developer Option
Developer Surrender or Deed-Back
The developer or association agrees to take the ownership back under a formal program or individual review. Eligibility may depend on the loan, fees, assessments, and account standing.
Ownership Transfer
Resale or Transfer to Another Party
The ownership moves to a buyer, family member, or other eligible recipient through an approved transfer. The process may require documentation, fees, lender approval, or developer processing.
Individual Review
Negotiated or Contract-Based Resolution
Unusual hardship, documented disputes, sales-practice concerns, or other facts may justify closer review. The outcome depends on the evidence, agreement terms, and parties involved.
Nonpayment Consequence
Default, Collections, or Foreclosure
Whatever path is used, the final documentation matters more than the label. Written confirmation should explain what happened to the ownership, purchase loan, unpaid balances, and responsibility for future fees.
The name of the path matters less than the final documentation. A valid resolution should clearly explain what happened to the ownership, loan, unpaid balances, and future fees.
Which Ownership Details Can Limit Your Post-Rescission Options?
ost-rescission options are often limited by the details of the ownership rather than simply by how much time has passed since the purchase.
Active financing can block or complicate surrender, resale, or transfer. A developer may require the loan to be paid off before accepting a deed-back, and transferring the ownership does not automatically transfer or eliminate a separate purchase loan.
Account status can also affect eligibility. Past-due maintenance fees, assessments, collection activity, or other balances may need to be resolved before a developer or association will process a surrender or approve a transfer.
The ownership structure and transfer rules matter as well. A deeded week, points interest, right-to-use agreement, trust interest, or membership may have different approval requirements, restrictions, and documentation.
The practical question is not simply whether an exit option exists in general. It is whether your ownership, financing, account status, and program rules allow that option to be completed.
Decision Insight
Resolving the Ownership and Resolving the Loan May Be Separate Issues
A deed-back, transfer, settlement, or other ownership resolution does not automatically eliminate an outstanding purchase loan. The financing may involve a separate lender, agreement, balance, and approval process.
Before accepting any proposed solution, confirm in writing what happens to both the ownership and the financing.
Risk Point
A Promise to Cancel Is Not Proof That the Obligation Ended
An exit-company agreement, verbal developer assurance, submitted surrender request, or pending transfer does not by itself prove that the timeshare has been resolved. The ownership, loan, fees, and account records may remain active while the proposed solution is still being reviewed.
Do not treat the process as complete until the appropriate developer, lender, association, title holder, or other responsible party provides written confirmation of the final outcome.
Action Step
Use This Checklist Before Choosing a Post-Rescission Option
Once the rescission period has closed, compare any proposed solution against the records that control the ownership, financing, account standing, and transfer or surrender requirements. Do not commit to a path until you know what it will—and will not—resolve.
Confirm the ownership and account records. Identify the deed, contract, membership, points interest, current owner of record, and present account status.
Verify the purchase loan separately. Request the current balance and confirm whether the proposed solution addresses the financing or only the ownership.
Identify unpaid fees and assessments. Confirm maintenance fees, assessments, late charges, collection balances, and other amounts that could affect eligibility or remain afterward.
Request written developer options. Ask whether surrender, deed-back, hardship review, owner assistance, transfer, or another internal process is available for the specific account.
Confirm approval and transfer requirements. Identify who must approve the process, what documents or fees are required, and whether financing or delinquency prevents completion.
Require written proof of the final outcome. The documentation should show what happened to the ownership, financing, unpaid balances, and responsibility for future charges.
Quick Win
Ask one question that forces the pieces together: “If this option is completed, what written documents will show that the ownership, loan, existing balances, and future fees have each been resolved?”
Why Some Post-Rescission Options Do Not Work
A post-rescission option can sound available in theory and still fail because one required piece of the process cannot be completed.
Developer surrender or deed-back may fail because the ownership does not meet the program’s eligibility rules. An active purchase loan, past-due maintenance fees, assessments, collection activity, ownership type, or other account conditions may prevent the developer or association from accepting the timeshare back.
Resale or transfer may fail because there is no qualified recipient—or because the recipient cannot be approved. Finding someone willing to take the timeshare is only one step. The transfer may still depend on developer approval, lender requirements, transfer fees, account status, closing documents, and formal changes to the ownership records.
Negotiated or hardship-based resolutions may fail because they are discretionary. A developer may review financial hardship, unusual circumstances, or a documented dispute without being required to approve a surrender, release a loan, forgive a balance, or terminate the ownership.
Third-party assistance may fail when the promised outcome depends on someone the service provider does not control. An exit company cannot force a developer to accept a surrender, create a resale buyer, make a lender release financing, or guarantee that an association will approve a transfer.
The process is not successful simply because paperwork was submitted, a fee was paid, or someone said the account was being handled. The meaningful endpoint is written documentation confirming what happened to the ownership, financing, existing balances, and responsibility for future fees.
Once payments are late or an account has entered collections, the owner may be dealing with two separate but connected problems: the unpaid balance and the continuing timeshare ownership.
Paying or settling a delinquent loan, maintenance-fee balance, assessment, or collection account may resolve some or all of the amount currently due. It does not necessarily transfer the timeshare, end the membership, eliminate future fees, or release an outstanding purchase loan.
Before agreeing to a payment plan or settlement, confirm who currently controls the account, what amount will be resolved, whether additional balances remain, and what happens to the ownership afterward. If the goal is also to end the timeshare, determine what separate surrender, transfer, foreclosure, termination, or other documented process would be required.
Nonpayment is not a cancellation method. It may change the account’s status and eventually lead to collections or enforcement, but the ownership should not be treated as ended until the appropriate records and written confirmation show that responsibility has actually changed.
If the account has already moved into collection activity, review Can a Timeshare Send You to Collections? for the broader collection process and what to verify before responding.
Owner Takeaway: After the rescission period ends, focus less on what an option is called and more on what it actually resolves. A surrender, transfer, settlement, foreclosure, or third-party process should not be treated as a completed exit until written documentation confirms what happened to the ownership, purchase loan, existing balances, and responsibility for future fees.
Frequently Asked Questions
These questions focus on what may still be possible after the ordinary rescission period has ended and how to verify whether a proposed resolution actually ends the ownership and related obligations.
Can you cancel a timeshare after the rescission period?
Usually not through the ordinary rescission process. Once the deadline has passed, the developer generally is not required to reverse the purchase simply because the owner no longer wants the timeshare.
Other paths may still exist, including surrender or deed-back, resale, transfer, negotiated resolution, hardship review, or review of specific contractual or sales-related concerns. Each path has its own requirements and should be verified separately.
What options may still exist after the rescission deadline?
Possible post-rescission paths may include a developer surrender or deed-back program, transfer or resale, hardship or owner-assistance review, negotiated resolution, or another contract-based process.
Availability can depend on the ownership structure, loan balance, account standing, unpaid fees, developer policies, and transfer restrictions. An option that exists in general may not be available for a specific ownership.
Can the developer take the timeshare back after rescission?
Sometimes. Some developers or associations offer surrender, deed-back, hardship, or owner-assistance programs after the rescission period has ended.
Eligibility may depend on whether the purchase loan is paid off, the account is current, maintenance fees and assessments have been addressed, and the ownership meets the program’s specific requirements.
Can you sell or transfer a timeshare after the rescission period?
Sometimes. A resale or transfer may still be possible, but finding someone willing to take the timeshare does not complete the process.
Developer approval, transfer restrictions, financing, unpaid fees, closing documents, transfer charges, and formal changes to the ownership records may all affect whether the transaction can actually be completed.
Does surrendering or transferring the timeshare cancel the loan?
Not automatically. The ownership interest and purchase financing may involve separate agreements, balances, and parties.
A surrender, deed-back, resale, or transfer should not be treated as eliminating the loan unless the written terms specifically explain what happens to the outstanding financing and any lender approval that is required.
Is stopping payments the same as canceling a timeshare?
No. Nonpayment may lead to late charges, collections, credit consequences, loss of usage rights, foreclosure, termination, or other enforcement, depending on the ownership and account.
It should not be treated as a voluntary cancellation method or proof that future ownership obligations have ended.
How do you know when a post-rescission exit is actually complete?
Obtain written documentation showing what happened to the ownership, purchase loan, unpaid balances, and responsibility for future maintenance fees or assessments.
A submitted surrender request, signed exit-company agreement, verbal assurance, pending transfer, or payment of a fee is not the same as a completed release. The final records should show that the responsible parties recognize the ownership and financial outcome.
Bottom Line
Once the rescission deadline passes, the ordinary cancellation process is generally no longer available.
Other paths may still exist, but they depend on the ownership structure, loan balance, account standing, developer policies, transfer restrictions, and the specific facts involved.
Do not treat the matter as resolved until written documentation confirms what happened to the ownership, financing, unpaid balances, and future responsibility.
Before You Choose a Post-Rescission Path
Understand Which Options Fit the Ownership You Actually Have
The Timeshare Decision Intelligence Report™ helps organize your ownership documents, loan status, fees, account standing, transfer restrictions, developer policies, verification gaps, and possible decision pathways before you stop paying, hire an exit company, or commit to another costly strategy.
Customized ownership review • Decision-support report • No exit-company sales pitch
Independent decision support. This is not legal advice, contract cancellation, an exit service, a resale service, lender negotiation, or a promise that the ownership can be surrendered, transferred, canceled, or otherwise resolved.
Related Guides
These guides provide more detail about rescission deadlines, broader exit planning, developer programs, and the financial risks that may arise after the cancellation window closes.
Rescission and Cancellation
- Timeshare Rescission Period: Can You Cancel a Timeshare After Signing?
Review how the initial cancellation window works, what the contract may require, and why proof of timely delivery matters.
Exit and Developer Options
- How to Get Out of a Timeshare: The Complete Exit Guide
Compare the broader resolution paths that may remain after the rescission period has passed. - What Is a Timeshare Deed-Back Program?
Learn how developer surrender programs may work and which eligibility requirements commonly apply. - Can You Sell a Timeshare Back to the Developer?
Understand the difference between a true developer repurchase, a deed-back, and other owner-assistance options.
Payment and Account Risks
- Should You Stop Paying Your Timeshare?
Review the possible consequences before treating nonpayment as an exit strategy. - Can a Timeshare Affect Your Credit Score?
Understand how financing, delinquent balances, collections, and reported activity may affect credit.