Financed Timeshare Exit Guide
Can You Get Out of a Timeshare If You Still Owe Money?
Yes, sometimes—but the ownership and the loan are separate obligations. Selling, transferring, surrendering, or otherwise ending the timeshare does not automatically cancel the financing used to buy it. The exit is only complete when both the ownership and the remaining debt are actually resolved.
The decision: Which exit paths are realistically available with your current loan balance, and what must happen to both the ownership and the financing before you are truly finished?
This guide explains how a remaining timeshare loan can affect surrender, resale, transfer, payoff, and other ownership-resolution paths. Financing, transfer rules, developer policies, account status, and lender requirements can vary by ownership and contract. For broader ownership-change options, see the Timeshare Exit Guide. If you are considering simply stopping payment, review Should You Stop Paying Your Timeshare? before treating nonpayment as an exit.
On This Page
- Can you get out if you still owe money?
- Ownership and financing are separate
- What changes your exit options?
- Paid off vs. still financed
- Can you surrender with a loan?
- Can you sell or transfer with a loan?
- What if you owe more than it is worth?
- Does getting out cancel the loan?
- What actually resolves the financing?
- Be careful with loan-elimination promises
- Compare realistic paths
- Which situation fits you?
- My Take
- Frequently asked questions
- TTCA Decision
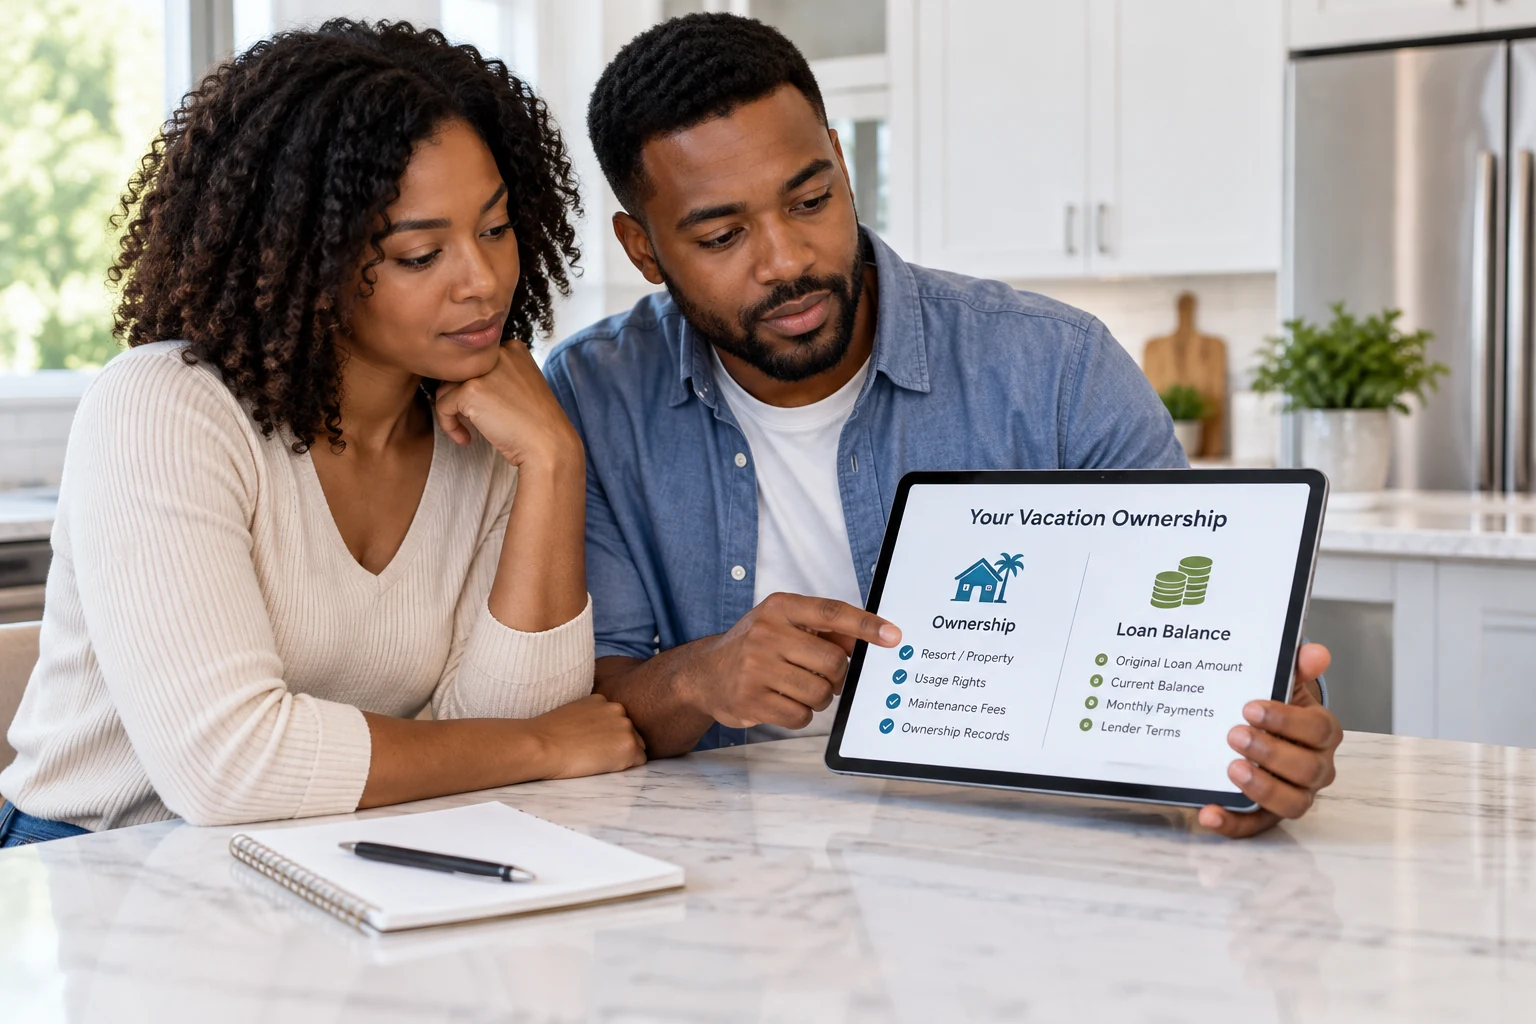
A financed timeshare involves two separate issues: the ownership itself and the loan used to purchase it. Both need to be understood before choosing an exit path.
Quick Answer
Yes, But the Loan Can Limit Which Exit Paths Are Realistic
You may be able to get out of a timeshare while you still owe money, but an outstanding loan can limit which exit paths are available and can require payoff, lender approval, or another documented resolution before the ownership can transfer cleanly.
The most important distinction is that ending the timeshare ownership and resolving the purchase loan are not automatically the same event.
Before choosing an exit path, confirm your current payoff amount, what the developer or lender requires, and what written documentation would prove that both obligations are finished.
Can you get out of a timeshare if you still have a loan?
Yes, sometimes—but the ownership and the financing are separate obligations. A sale, transfer, surrender, or other ownership change does not automatically cancel the loan used to buy the timeshare.
A financed exit is complete only when both sides are resolved: documentation shows that you no longer own the timeshare, and separate documentation shows that the remaining loan has been paid, settled, released, refinanced, or otherwise resolved with the lender.
Start With the Structure
A Financed Timeshare Creates More Than One Obligation
- Ownership The deed, vacation-ownership interest, membership, or points rights that determine what you own and what must be transferred, surrendered, or otherwise ended.
- Financing The loan or credit obligation used to purchase the ownership. This is a separate debt relationship with its own balance and lender requirements.
- Recurring charges Maintenance fees, Club dues, assessments, and other ownership-related charges may continue until the ownership itself is properly resolved.
What Changes the Answer
The Loan Balance Is Only One Factor
- Current payoff amountThe amount required to satisfy the loan today may be different from the balance shown on an older statement.
- Account statusA current account may have options that become harder to use after delinquency or default.
- Ownership structureDeeded, points-based, membership, or other structures can have different transfer and surrender requirements.
- Developer surrender rulesSome programs require financing to be paid off; others may evaluate financed owners individually.
- Realistic resale valueThe market value of the ownership determines whether sale proceeds can meaningfully reduce the payoff.
- Lender closing requirementsThe lender may require payoff, settlement, or another approved process before releasing the borrower.
- Outstanding feesPast-due maintenance fees, assessments, or Club charges can complicate transfer or surrender.
- Transferable benefitsA buyer may value the ownership differently depending on what benefits actually survive resale or transfer.
Important Distinction
Paid-Off Owners and Financed Owners Are Solving Different Problems
If the timeshare is paid off
- the purchase financing is no longer the barrier;
- the main question is how to resolve the ownership itself;
- maintenance fees or other recurring charges may still continue; and
- surrender, resale, or transfer may still depend on program rules and market demand.
If the timeshare is still financed
- the ownership still has to be resolved;
- the loan also needs its own resolution;
- the remaining balance can block or complicate surrender or transfer; and
- a resale may require enough proceeds or cash to satisfy a payoff shortfall.
TTCA Ownership PathFinder™
Keep, rent, sell or exit?
A remaining loan can change which ownership paths are realistic, but it does not by itself determine whether Keep, Rent, Sell, or Exit is the right starting point.
Answer five quick questions to compare the broader paths based on what you own, the value you still receive, what it costs, your financing, and what you want next.
Complimentary for TTCA visitors • About 2 minutes
You decide what happens next. We help you understand the paths.
Direct Resolution
Can You Surrender or Deed Back a Timeshare With a Loan?
Sometimes, but direct surrender programs vary significantly. Some developers require the purchase financing to be paid off before they will accept the ownership back. Others may evaluate financed owners individually or offer a different path depending on account status and the remaining balance.
Before assuming surrender is available, ask two separate questions:
- Will the developer accept the ownership while financing remains?Do not assume the deed-back or surrender program applies to a financed account simply because it exists for paid-off owners.
- If the ownership is accepted, what happens to the outstanding loan?A surrender agreement should not be assumed to cancel the financing unless the lender or responsible party confirms that result in writing.
For a broader look at direct return programs, see Timeshare Deed-Back Programs: Can You Give It Back?
If you have already checked the developer’s direct options and still need help exploring resale, transfer, or another ownership-resolution path, Timeshare Specialists can provide an outside consultation.
Request a ConsultationSelling or Transferring
Can You Sell or Transfer a Timeshare You Still Owe Money On?
Finding a buyer or recipient is only the first step. The ownership and the financing still have to be coordinated so that the transaction can actually close and the original borrower is properly released where required.
Finding a buyer does not transfer the loan
A buyer agreeing to take the timeshare does not automatically mean the buyer takes over the original financing. The loan is generally tied to the borrower under the existing credit agreement unless the lender formally approves another arrangement.
Calculate the payoff gap before listing
Compare the current written payoff amount with realistic resale proceeds—not the original purchase price or what you hope the timeshare is worth.
Can the sale proceeds pay off the loan?
They may be applied toward the payoff if the transaction is structured that way and the lender accepts the closing process. If the proceeds are not enough, the seller may need to bring money to closing or reach another lender-approved resolution.
Do not rely on an informal “take over my payments” arrangement
Unless the lender formally releases the original borrower and the ownership transfer is completed correctly, an informal payment arrangement may leave the seller responsible for both the debt and the timeshare.
Paying off the loan improves transferability—not necessarily market value
Removing the financing can make surrender, sale, or transfer easier to complete. It does not create buyer demand. Annual fees, resale restrictions, reduced resale benefits, and the underlying market for the ownership can still limit what a buyer is willing to pay.
If you understand the payoff requirement and still need an outside perspective on resale, transfer, or another ownership-resolution path, Timeshare Specialists can provide a consultation.
Request a Consultation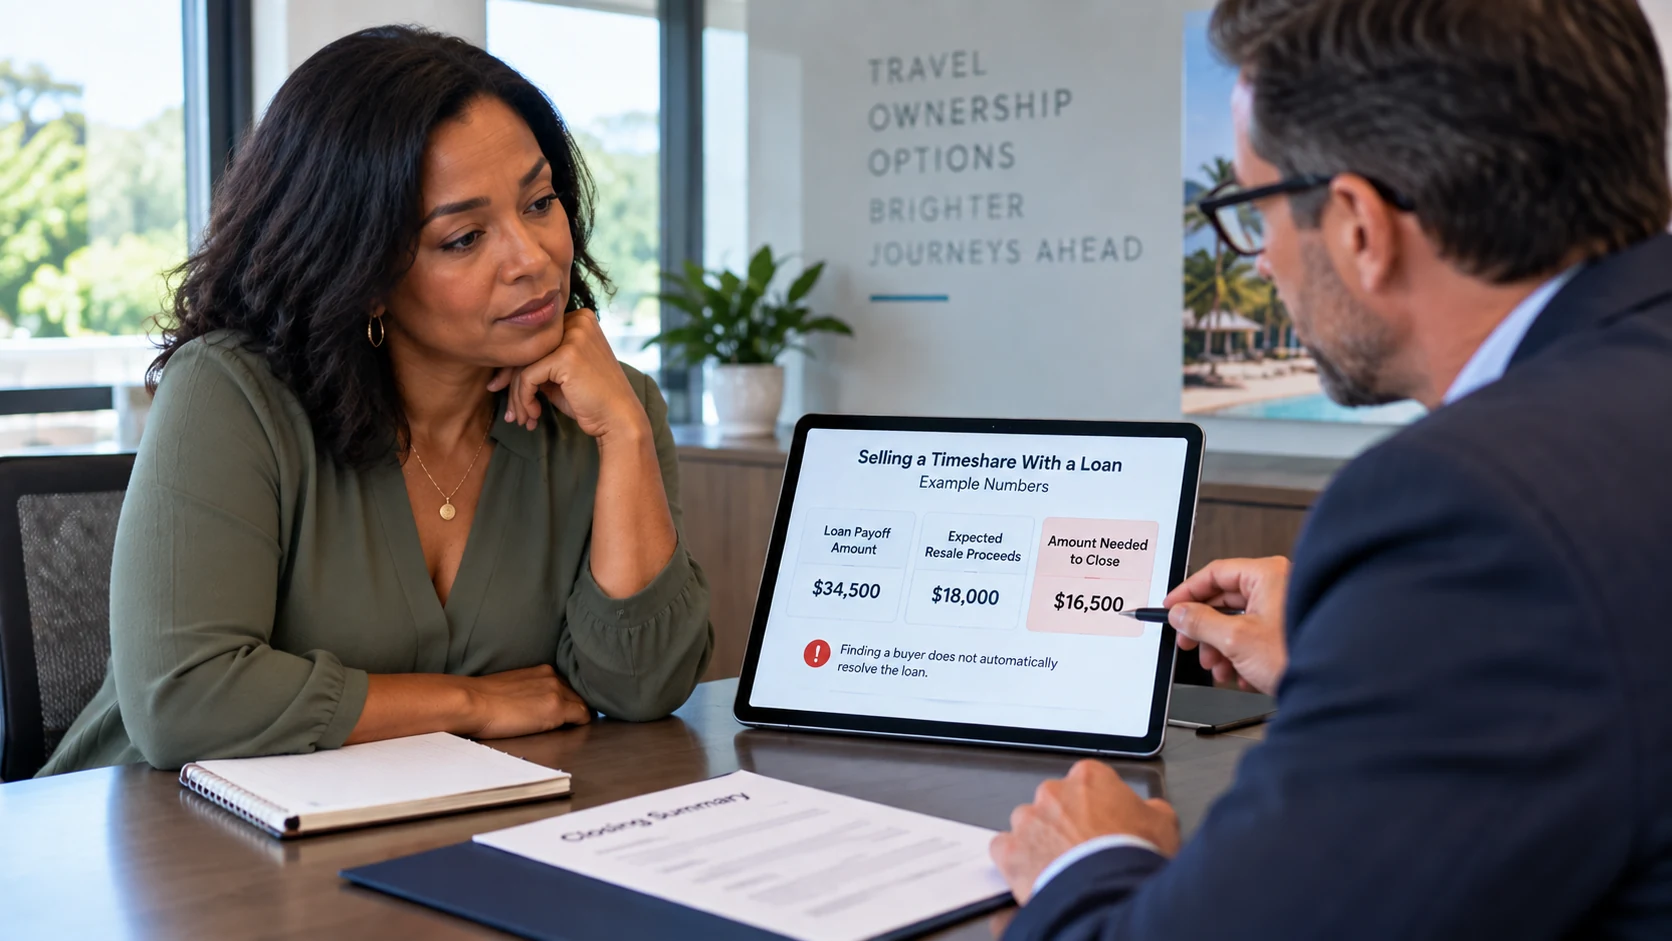
Finding a buyer does not automatically resolve a financed timeshare. The loan payoff, expected resale proceeds, and any remaining shortfall all need to be addressed before the ownership can transfer cleanly.
The Payoff Gap
What If You Owe More Than the Timeshare Is Worth?
This is where many financed exits become difficult. The resale market does not care what you originally paid. It reflects what another buyer is willing to pay for the ownership now.
If the current loan payoff is substantially higher than realistic resale proceeds, selling may still be possible—but someone has to resolve the difference.
Two Separate Outcomes
Does Getting Out of the Timeshare Cancel the Loan?
Not necessarily.
A surrender, transfer, sale, foreclosure, or other ownership change should not be assumed to eliminate the financing unless the lender confirms that the debt has been paid, settled, released, refinanced, or otherwise resolved.
Document 1: What proves I no longer own the timeshare?
Document 2: What proves I no longer owe the loan?
If you cannot answer both questions with documentation, do not assume the financed exit is complete.
Loan Resolution
What Would Actually Resolve the Financing?
The appropriate outcome depends on the loan and lender. Possible documented resolutions can include:
- Full payoffThe remaining loan is paid in full.
- Sale proceeds plus seller fundsResale proceeds reduce the payoff and the seller covers the remaining shortfall.
- Lender-approved settlementThe lender agrees in writing to accept an approved amount or arrangement in satisfaction of the debt.
- Negotiated resolutionThe lender approves another documented way to resolve the remaining obligation.
- Refinancing or separate debt resolutionThe original timeshare financing is replaced or otherwise resolved through another approved financial arrangement.
None of these outcomes should be assumed to be available simply because they are possible in other situations. The lender’s written terms control the actual result.
What I Would Verify
Be Careful With “Loan Elimination” Promises
A company saying it can “cancel,” “wipe out,” or “eliminate” a timeshare loan is not the same thing as your lender issuing a written release.
Before relying on a third-party promise, I would want clear answers to:
- Who is actually negotiating with the lender?
- Does the lender have to approve the result?
- What happens if the loan remains unpaid during the process?
- Could the account become delinquent or enter collections?
- What document proves the lender released the borrower?
If a proposed strategy depends on stopping payments, review Should You Stop Paying Your Timeshare? before treating nonpayment as part of an exit plan.
The Tradeoff
Compare the Realistic Paths for a Financed Timeshare
- Developer surrender Potentially simpler and more direct, but eligibility may depend on the loan being paid off or otherwise resolved.
- Resale or transfer Preserves the possibility of moving the ownership to someone else, but the payoff gap can make the transaction impractical.
- Loan payoff or negotiated resolution Can remove the financing barrier, but may require cash, lender cooperation, or another approved financial arrangement.
- Outside assistance May help when direct paths are not workable, but the provider should be evaluated based on what it actually resolves and whether lender cooperation is still required.
If you have already reviewed the developer and lender requirements and still need help comparing resale, transfer, or another ownership-resolution path, Timeshare Specialists can provide an outside consultation.
Request a ConsultationHow does financing affect the four broader ownership paths?
- Keep
- Continue with the ownership if the vacation value still justifies the annual cost and the loan payment remains manageable. Financing can affect affordability even when the ownership itself still works well.
- Rent
- Keep the ownership while exploring whether eligible unused usage can help offset some recurring costs. Rental income does not eliminate the loan, and program rules may restrict what can be rented.
- Sell
- Explore resale or transfer where a realistic market exists, but compare expected proceeds with the current payoff amount. Any shortfall still has to be resolved before a clean transfer can usually be completed.
- Exit
- Explore developer surrender, deed-back, negotiated resolution, or another legitimate ownership-resolution path. A remaining loan may limit eligibility and generally requires its own documented resolution.
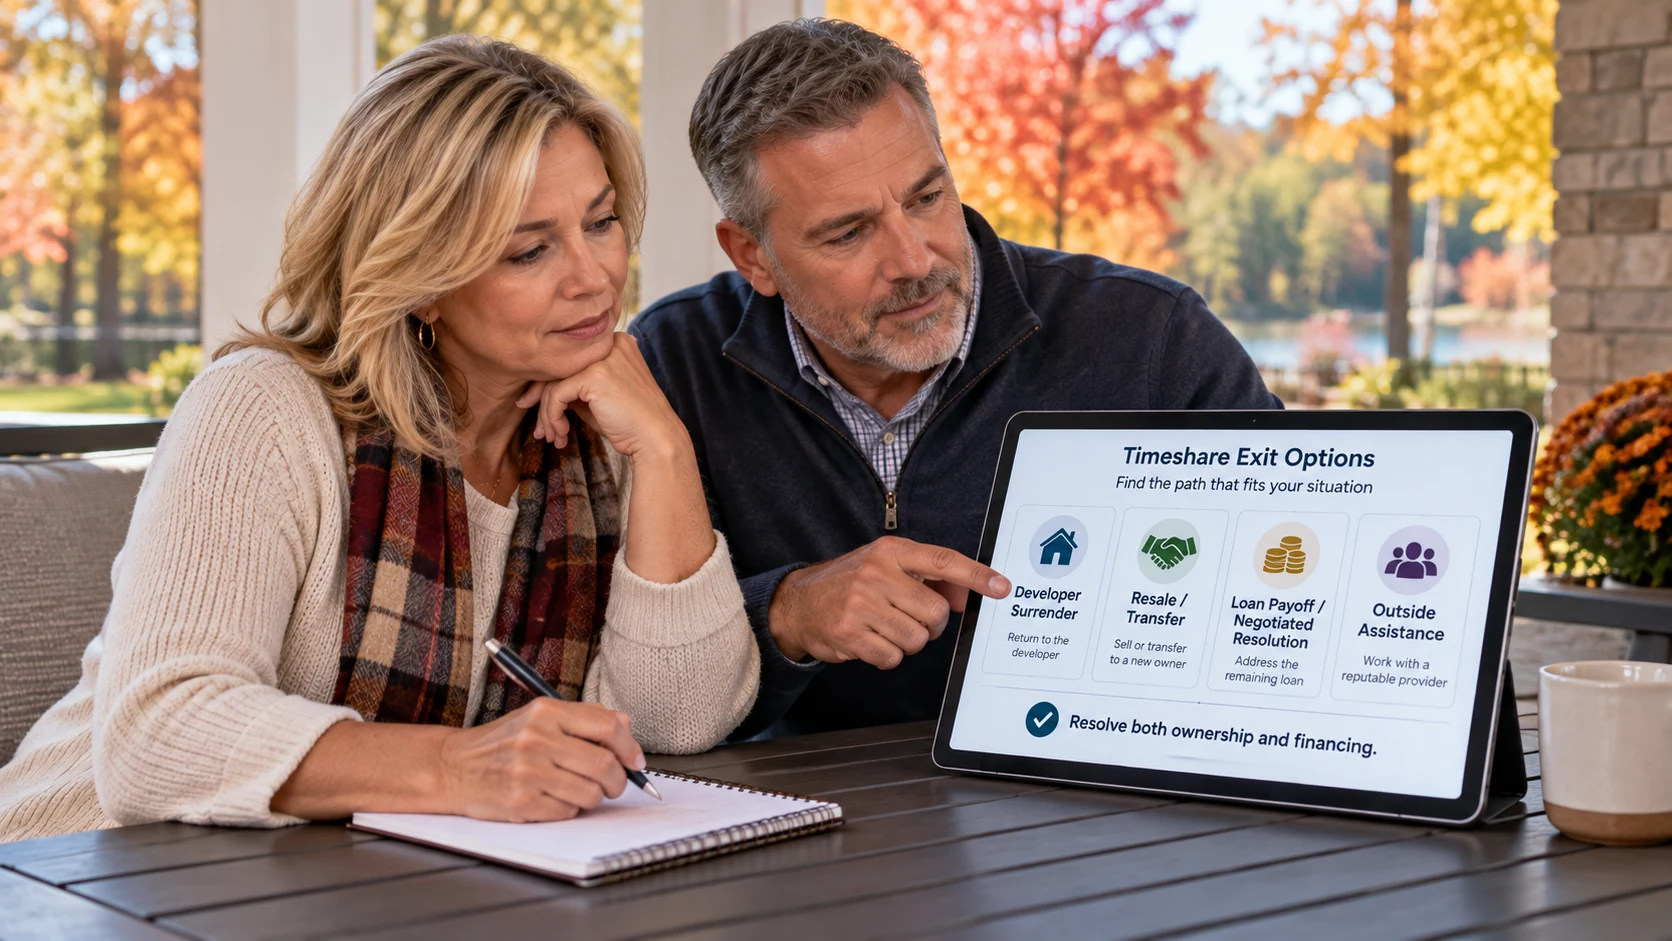
A financed-timeshare exit is only complete when both the ownership and the remaining loan are resolved. The available path may involve surrender, resale or transfer, loan payoff or negotiation, or outside assistance.
Which Situation Fits You?
The Loan Economics Can Point You Toward Different Paths
A direct or conventional path may deserve first consideration if:
- your account is current;
- the remaining loan is manageable;
- the developer has a surrender program;
- realistic resale proceeds cover much of the payoff;
- you can fund a reasonable closing shortfall; or
- a qualified transferee is available.
A more complicated resolution may be needed if:
- the loan greatly exceeds realistic resale value;
- the developer requires payoff before surrender;
- the account is already delinquent;
- maintenance fees are also past due;
- you cannot fund the payoff gap; or
- you are receiving promises that the loan can simply be “eliminated.”
My Take
I Would Treat the Loan as a Separate Exit Problem
If I still owed money on a timeshare, I would not start by asking which exit company could take the ownership away.
I would first get the current payoff amount, confirm what the developer requires for surrender or transfer, and compare that balance with what the ownership could realistically sell for.
Only then would I know which exit paths are actually feasible.
For me, the exit would not be complete until I had written proof that both the ownership and the financing were resolved.
Keep the exit decision focused on what actually has to be resolved.
Get independent TTCA guidance on financed ownership, surrender, resale, transfer, and next-step decisions.
Frequently Asked Questions
Questions About Getting Out of a Financed Timeshare
Can you deed back a timeshare if you still owe money?
Sometimes, but many deed-back or surrender programs require the loan to be paid off or otherwise resolved first. Ask the developer what applies to the specific ownership and what happens to the financing if the ownership is accepted back.
Can you sell a timeshare with a loan balance?
Potentially, but the loan normally has to be addressed as part of the transaction. If resale proceeds are lower than the payoff amount, the seller may need to cover the shortfall or obtain another lender-approved resolution before the transfer can close.
Can someone take over your timeshare loan payments?
Do not assume an informal payment arrangement transfers the debt. Unless the lender formally approves the change and releases the original borrower, the original borrower may remain responsible for the loan.
What if you owe more than the timeshare is worth?
The difference between the loan payoff and realistic resale proceeds still has to be resolved. Finding a buyer does not erase the shortfall.
Does transferring a timeshare remove the loan?
Not automatically. The ownership transfer and the financing are separate transactions. The lender must confirm what resolves or releases the loan obligation.
Can a timeshare exit company cancel your loan?
A third party can make promises or attempt to negotiate, but the lender controls whether the financing is paid, settled, released, refinanced, or otherwise resolved. Do not treat a marketing promise as the equivalent of a written lender release.
What documents prove a financed timeshare exit is complete?
You should be able to identify documentation proving the ownership has ended or transferred and separate documentation proving the loan has been paid, settled, released, or otherwise resolved. One does not automatically prove the other.
TTCA Decision
A Financed Timeshare Exit Has to Resolve Both the Ownership and the Loan
You may be able to surrender, sell, transfer, or otherwise exit a timeshare while financing remains, but the loan can materially limit which paths are realistic.
Finding a buyer, signing a surrender agreement, or changing the ownership record does not automatically eliminate the debt.
The exit is complete only when you can document both outcomes: you no longer own the timeshare, and you no longer owe the financing associated with it.
Continue From Here
Keep Working Through the Parts of the Exit That Still Need Resolution
Should You Stop Paying Your Timeshare?
Understand what default can trigger and why stopping payment does not automatically end the ownership or the debt.
Timeshare Deed-Back Programs: Can You Give It Back?
Review how direct surrender programs work and what account or financing requirements may affect eligibility.
How to Verify a Timeshare Exit Is Complete
See what documentation can help confirm that ownership, loan obligations, and future charges have actually ended.
Free Timeshare Self-Review
Take a clearer look at how the financed ownership fits your situation.
The Timeshare Self-Review helps you step back from the immediate exit question and look at how the ownership is working for you overall.
- How often you use it
- Your annual ownership costs
- Your booking experience
- The benefits you actually use
- Fit with your travel habits
- Ownership factors worth reviewing