Can You Sell a Timeshare If You Still Owe Money on It?
Selling a timeshare can become much more complicated when the purchase loan has not been paid off.
An owner may find a buyer who is willing to take the ownership, but that does not mean the loan can move with it. Timeshare financing is usually tied to the original borrower, and the developer or lender may require the balance to be paid before approving a transfer.
The difficult part is that the timeshare’s resale value may be far lower than the amount still owed.
That can leave an owner with a payoff gap: the difference between what a buyer is willing to pay and what must be paid to release the loan and complete the transfer.
Paying off the loan may remove one major barrier, but it does not guarantee that the timeshare will sell. Buyer demand, maintenance fees, transfer restrictions, and reduced resale benefits may still affect the outcome.
The more useful question is not simply:
“Can I sell my financed timeshare?”
It is:
“Can the ownership be transferred while the loan is active, what amount must be paid at closing, and would the likely sale proceeds cover that obligation?”
This guide explains how an active loan affects resale, transfer approval, payoff requirements, and the options an owner may need to evaluate when the balance exceeds the timeshare’s likely resale value.
Quick Answer
Can You Sell a Timeshare If You Still Owe Money on It?
A financed timeshare may sometimes be sold, but the outstanding loan usually must be paid off or otherwise resolved before ownership can be transferred. Most buyers cannot simply assume the original owner’s loan.
Whether a sale can close depends on the lender’s payoff requirements, the developer’s transfer rules, the current account status, and whether the sale proceeds are enough to cover the remaining balance.
What Changes When a Timeshare Still Has a Loan?
A timeshare sale normally involves transferring the ownership from the current owner to a buyer. An active loan adds a second obligation that must be addressed before that transfer can be completed.
The loan agreement is generally between the original borrower and the developer or lender. A buyer may be willing to accept the timeshare itself, but that does not mean the buyer can take over the existing financing.
The lender may require a full payoff before releasing its interest in the account. The developer or management company may also refuse to process the ownership transfer until the loan is cleared and the account is current.
This means a potential sale can involve several separate approvals:
- The buyer agrees to accept the ownership.
- The lender provides a current payoff amount.
- The loan balance is paid or otherwise resolved.
- The developer confirms that transfer requirements have been satisfied.
- The ownership records are formally changed.
Until those steps are completed, the original owner may remain responsible for the loan, maintenance fees, assessments, and other account obligations.
Important Distinction
Selling the Timeshare and Resolving the Loan Are Separate Steps
A buyer’s agreement to take the timeshare does not automatically release the original owner from the financing. The loan may need to be paid in full even when the ownership itself is being sold for a small amount.
Before accepting an offer, confirm who must receive the payoff, when it must be paid, and what written release is required before the ownership transfer can close.
Before You List a Financed Timeshare
Determine Whether the Loan, Transfer Rules, and Resale Value Can Work Together
The Timeshare Decision Intelligence Report™ helps organize your payoff balance, ownership documents, account standing, transfer restrictions, likely cost exposure, and unresolved questions before you accept a buyer, pay a resale company, or assume the sale proceeds will cover the loan.
Need a clearer view before trying to sell with a loan balance?
Review the Report Option Independent decision support • No resale or exit-company sales pitchWhy Most Buyers Cannot Simply Take Over the Loan
Timeshare financing is usually based on the original purchaser’s credit, income, and agreement with the lender or developer.
Because of that, the loan generally does not move automatically when the ownership is sold. A buyer may be approved to receive the timeshare but still be unable to assume the seller’s financing.
Even when a contract does not expressly prohibit an assumption, the lender may require a separate review, new financing, or full payoff before releasing the original borrower.
This creates an important distinction:
- The buyer may agree to take the timeshare.
- The lender may still hold the original owner responsible for the debt.
An informal agreement in which the buyer promises to make the remaining payments can create substantial risk. Unless the lender formally releases the seller, missed payments may continue to affect the original borrower.
What Happens When the Loan Balance Exceeds the Resale Value?
Many owners discover that the amount owed is substantially higher than what buyers are willing to pay.
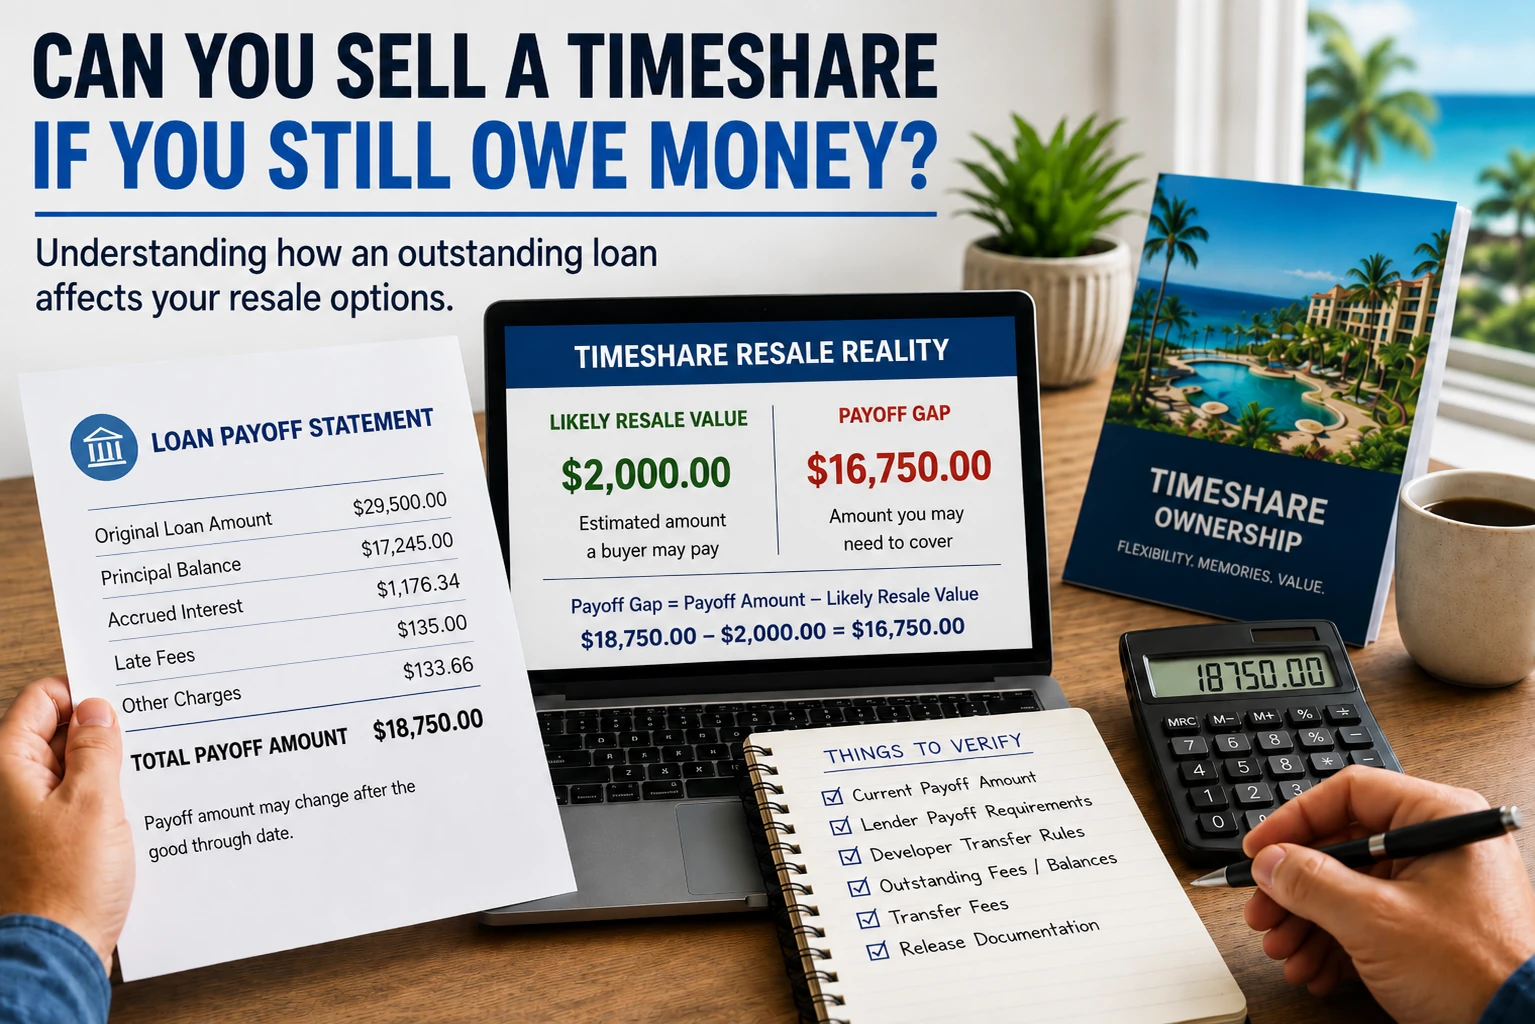
For example, an owner might owe $18,000 while comparable resale listings attract offers of only a few hundred or a few thousand dollars. In that situation, selling does not eliminate the debt. The owner may need to pay the difference before the transfer can close.
This difference is sometimes called a payoff gap.
The payoff gap may include more than the remaining principal. A current payoff statement may also reflect accrued interest, late charges, unpaid maintenance fees, transfer costs, or other account balances.
Before listing the timeshare, request a written payoff amount and compare it with realistic resale prices for similar ownerships. The original purchase price is not a reliable measure of what the resale market may pay.
Transfer Conditions
Financed Ownership vs. Paid-Off Ownership
Paying off the loan can remove a major transfer barrier, but it does not create resale demand or guarantee that the ownership will sell.
Additional Barriers
Financed Timeshare
- The lender may require full payoff before transfer.
- The buyer usually cannot assume the existing financing.
- The payoff amount may exceed the likely resale price.
- Loan delinquency may create additional approval or collection issues.
- The owner may need to contribute money for the sale to close.
One Barrier Removed
Paid-Off Timeshare
- No purchase-loan payoff is required before transfer.
- The transaction may involve fewer parties and approvals.
- The seller does not need sale proceeds to satisfy financing.
- Transfer may still require a current account and completed paperwork.
- Buyer demand, fees, and resale restrictions still affect the outcome.
Paying off the loan improves transferability—not necessarily market value. A paid-off timeshare can still be difficult to sell when annual fees, buyer restrictions, or weak demand reduce its appeal.
Can the Sale Proceeds Pay Off the Loan at Closing?
Possibly, but only when the transaction is structured to satisfy the lender’s payoff requirements.
In some sales, funds from the buyer may be applied toward the outstanding balance as part of the closing process. The lender would then need to confirm that the required amount was received and that its interest in the account can be released.
The problem arises when the buyer’s payment is lower than the payoff amount. The seller may need to contribute the difference before the lender or developer will approve the transfer.
Before relying on the sale proceeds, confirm:
- The exact payoff amount and how long the quote remains valid
- Whether the lender permits payoff through a resale closing
- Who will hold and distribute the buyer’s funds
- Whether maintenance fees and other balances must also be paid
- What release or account-closure documentation will be issued
- Whether the transfer can be completed immediately after payoff
Do not send money or transfer documents based only on a buyer’s or resale company’s assurance that the loan will be handled later. The payoff and transfer process should be documented before ownership changes hands.
Why Paying Off the Loan Does Not Guarantee a Sale
Paying off the purchase loan can remove one of the largest barriers to transfer, but it does not create buyer demand.
A prospective buyer will still consider the annual maintenance fees, booking rules, transfer costs, resale restrictions, available benefits, and the number of similar ownerships already on the market.
Some programs also limit benefits for resale purchasers. A buyer may receive the basic ownership or usage rights without the status levels, exchange privileges, discounts, or reservation advantages originally presented to the developer purchaser.
This means a paid-off timeshare may be easier to transfer while still having little resale value. Loan payoff improves the mechanics of a possible sale, but the ownership must still appeal to someone willing to accept its future obligations.
What If You Cannot Cover the Payoff Gap?
An owner may be unable or unwilling to contribute the money needed to pay off the loan before transfer.
In that situation, lowering the listing price usually does not solve the underlying problem. A lower price may attract more interest, but it also leaves less money available to satisfy the lender.
The owner may need to ask the lender whether any documented settlement, hardship, refinancing, or other account-resolution process exists. The developer may also have an owner-assistance or surrender program, although active financing often limits eligibility.
These alternatives should not be assumed. A developer surrender program may address the ownership without releasing the loan, and a lender resolution may address the debt without transferring the timeshare.
Before choosing another path, determine what would happen separately to the financing, ownership records, unpaid fees, and future maintenance obligations.
Risk Point
An Informal Buyer Arrangement Can Leave the Loan in Your Name
Allowing another person to use the timeshare and make the payments does not necessarily transfer either the ownership or the financing. Unless the lender formally releases the original borrower and the ownership records are properly changed, the seller may remain responsible for missed payments, fees, assessments, and other account activity.
Do not rely on a private promise that the buyer will “take over everything.” Require written lender approval, completed transfer documents, and confirmation that the original owner has been released.
What to Verify Before Listing or Accepting an Offer
Before advertising a financed timeshare, request a current payoff statement and confirm whether the lender allows the balance to be paid through a resale closing.
Then contact the developer, association, or management company to verify the transfer process. Ask whether the loan must be fully paid, whether the account must be current, which transfer fees apply, and whether the buyer will receive different benefits from a developer purchaser.
The likely resale value should also be compared with the payoff amount. Use comparable ownerships—not the original purchase price—to estimate what a buyer may realistically pay.
Finally, determine who will handle the closing and distribute the funds. A legitimate process should explain how the lender will be paid, how the ownership records will be changed, and when the seller’s responsibility for future fees ends.
Action Step
Confirm the Numbers and Transfer Rules Before You List
A financed timeshare should not be listed until you understand what must be paid, who must approve the transfer, and how much money may be required from you at closing.
Request a written payoff statement with the amount, expiration date, and payment instructions.
Confirm lender requirements for paying and releasing the financing during a resale closing.
Verify transfer eligibility directly with the developer, association, or management company.
Check the entire account balance including fees, assessments, late charges, and transfer costs.
Compare realistic resale prices with the amount required to complete the transfer.
Identify the closing process and the documents that will release you from the loan and ownership.
Quick Win
Calculate the payoff gap before advertising the timeshare. Subtract the likely resale proceeds from the total amount required to pay off the loan, clear any outstanding account balances, and complete the transfer.
What If Resale Is Not Realistic With the Current Loan?
When the payoff amount is much higher than the likely resale value, repeatedly lowering the listing price may make the financial gap larger rather than solve it.
One option may be to continue using the ownership while paying down the balance, provided the timeshare still fits the owner’s travel needs and budget. Another may be to ask the lender whether any documented hardship, settlement, or account-resolution process is available.
The developer may also offer a surrender, deed-back, or owner-assistance program. However, many programs require the purchase loan to be paid off and the account to be current before the ownership will be considered.
Transferring the timeshare to a friend or family member does not necessarily solve the problem either. The financing may remain in the original borrower’s name unless the lender approves a formal release.
If resale is blocked by the loan, the decision should shift from simply finding a buyer to determining which path could address both the debt and the ownership.
If selling is only one of the possibilities you are considering, see how to evaluate broader timeshare exit options when you still owe money, including surrender, transfer, financing resolution, and what must be verified before treating an exit as complete.
Owner takeaway: Before trying to sell a financed timeshare, compare the complete payoff amount with realistic resale proceeds and confirm what must happen for both the loan and ownership to be formally released.
❓ Frequently Asked Questions
These answers address the most common questions owners face when trying to sell a timeshare that still has an outstanding purchase loan.
Can you sell a timeshare if you still owe money on it?
Possibly, but the loan usually must be paid off or otherwise resolved before the ownership transfer can be completed. The lender’s payoff requirements and the developer’s transfer rules should both be confirmed before listing the timeshare.
Can a buyer assume an existing timeshare loan?
Usually not. Timeshare loans are commonly personal agreements tied to the original borrower. A buyer may need separate financing, while the seller remains responsible for paying off the original loan.
Can sale proceeds be used to pay off the loan?
They may be used as part of a properly documented closing. The lender must confirm the payoff amount and how the funds should be delivered. If the sale proceeds are lower than the payoff, the seller may need to contribute the difference.
What happens if I owe more than the timeshare is worth?
The owner may face a payoff gap between the amount required by the lender and what a buyer is willing to pay. That difference generally must be addressed before the lender releases the account and the transfer can close.
Will paying off the loan make the timeshare easy to sell?
Not necessarily. Paying off the loan removes a major transfer barrier, but buyer demand may still be limited by maintenance fees, competing listings, transfer costs, booking restrictions, or reduced resale-buyer benefits.
Can the developer take back a timeshare with an active loan?
Some developers review financed ownerships individually, but many surrender or deed-back programs require the loan to be paid off. Any offer should clearly state what happens to both the ownership and the remaining debt.
Can I transfer the timeshare to a friend or relative and keep the loan?
A private arrangement does not automatically release the original borrower. Unless the lender approves the change and the ownership records are formally transferred, the original owner may remain responsible for the loan and account obligations.
What if the loan or maintenance fees are already delinquent?
Delinquency may make transfer more difficult and can lead to late charges, collections, credit reporting, or enforcement. The complete account status should be verified before attempting a sale or agreeing to a proposed resolution.
How do I know I am no longer responsible after the sale?
Obtain written confirmation that the loan has been paid or otherwise resolved, the ownership records have been changed, outstanding account balances have been addressed, and responsibility for future fees has ended.
Bottom Line
You may be able to sell a timeshare while money is still owed, but the loan generally cannot be ignored or informally passed to the buyer.
Before listing the ownership, obtain the complete payoff amount, confirm the lender’s release requirements, verify the developer’s transfer process, and compare the likely resale proceeds with the amount needed to close.
Paying off the loan may make transfer easier, but it does not guarantee buyer demand or meaningful resale value.
Before You Try to Sell With a Loan Balance
Understand the Payoff Gap, Transfer Rules, and Other Paths Before You Commit
The Timeshare Decision Intelligence Report™ helps organize your loan status, payoff exposure, ownership documents, account standing, transfer restrictions, realistic resale barriers, verification gaps, and possible decision pathways before you list, stop paying, or hire a resale or exit company.
Customized ownership review • Decision-support report • No resale or exit-company sales pitch
Independent decision support. This is not legal advice, lender negotiation, contract cancellation, an exit service, a resale service, or a promise that the loan or ownership can be sold, surrendered, transferred, settled, or otherwise resolved.
Related Guides
These guides provide more detail about resale barriers, market value, developer programs, and broader exit options.
Resale and Market Value
- Why Can’t I Sell My Timeshare? What May Be Blocking a Sale
Review the other factors that can prevent a sale, including fees, buyer demand, transfer restrictions, and limited resale benefits. - Why Are Timeshares So Hard to Sell?
Learn why oversupply, weak buyer demand, and ongoing ownership costs can make the resale market difficult.
Developer and Exit Options
- Can You Sell a Timeshare Back to the Developer?
Understand the difference between a developer repurchase, surrender request, and deed-back program. - What Is a Timeshare Deed-Back Program?
Review how developer take-back programs may work and why an active loan can affect eligibility. - How to Get Out of a Timeshare: The Complete Exit Guide
Compare resale, surrender, transfer, developer programs, and other ownership-resolution paths.